


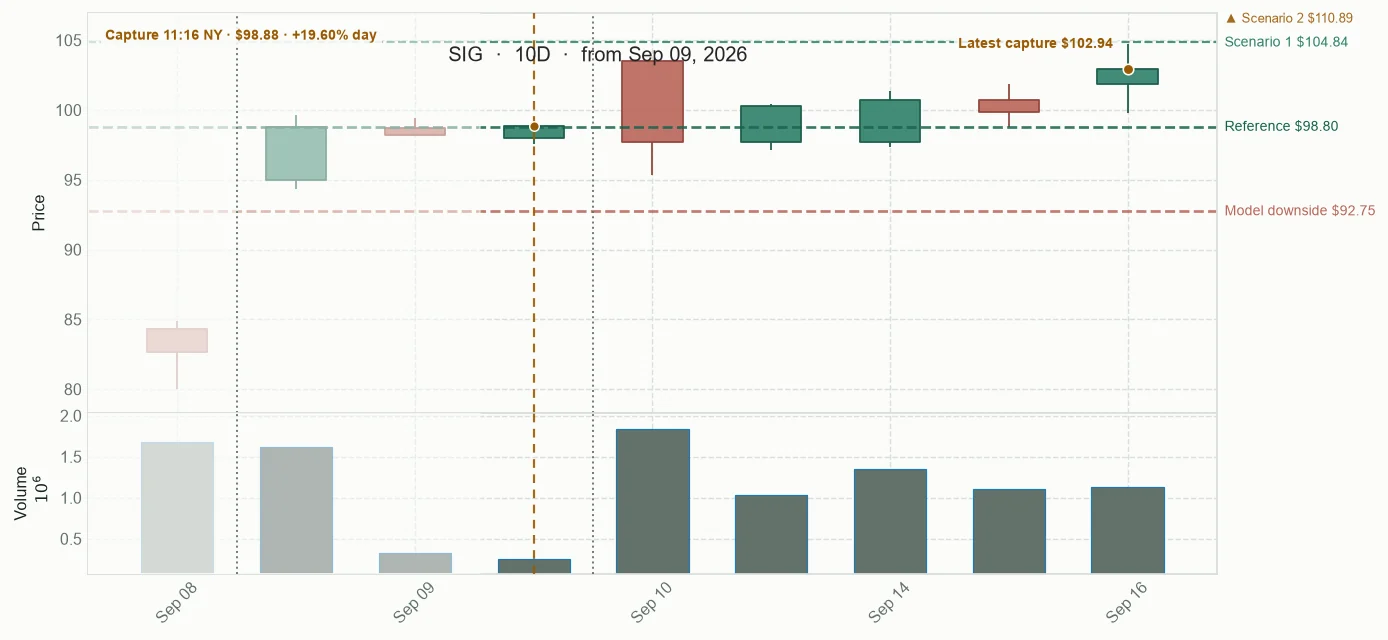
Panel thesis: SIG is provisionally selected because its primary earnings event, strong participation and above-VWAP reaction form the clearest current mechanism-to-tape link in the compared set. The thesis remains conditional because the stock is extended, near its 52-week high and still requires confirmation beyond the initial repricing.
+19.51% · 2.43x volume · 86.31 > 86.33 > 87.53

Company context
Signet Jewelers Limited operates as a diamond jewelry retailer in the United States, Canada, the United Kingdom, and Republic of Irland. It operates through three segments: North America, International, and other. The North America segment operates jewelry stores in malls, mall-based kiosks, and off-mall locations in the United States and Canada primarily under the Kay, Zales, Jared Jewelers, Diamonds Direct, Banter by Piercing Pagoda, Peoples Jewellers, and Rocksbox brands, as well as operates online through its digital brands, James Allen and Blue Nile. The International segment operates stores in shopping malls, off-mall locations, and online primarily under the H.Samuel and Ernest Jones brands in the United Kingdom and the Republic of Ireland. The Other segment engages in the purchase and conversion of rough diamonds to polished stones, as well as offers diamond polishing services. Signet Jewelers Limited was founded in 1862 and is based in Hamilton, Bermuda.
Committee read
This is the committee's read of the evidence, not a probability or score. Support comes from a primary earnings disclosure and an above-VWAP reaction that held in a weak session. The counter-case is near-high extension, flat sales guidance, short interest and a negative latest-quarter operating-cash-flow level. Fifteen-session persistence and current-to-prepared-period reconciliation remain unresolved. These percentages express committee balance, not calibrated probabilities.
Observed price path
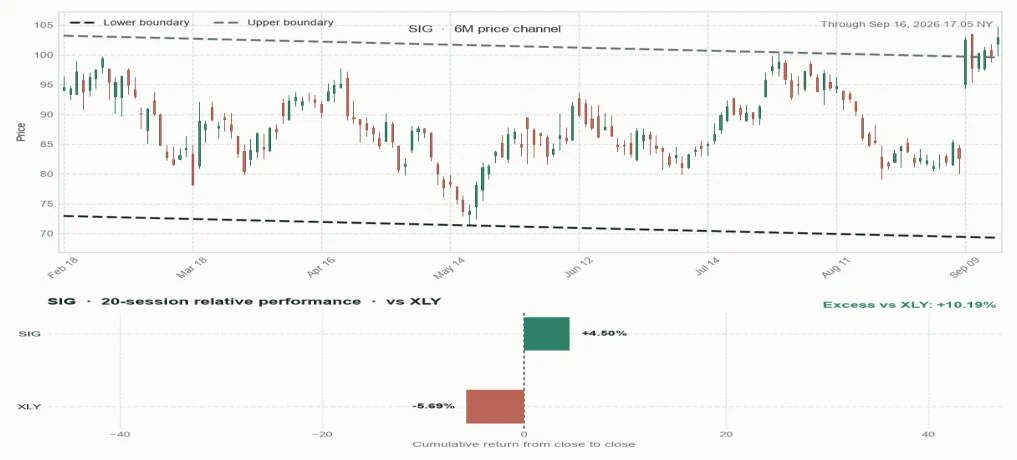
Price channel and relative performance
Public scanner fields captured at the base snapshot; deeper research inputs remain private.
Snapshot
What was captured at the base
Structure
How price is behaving
Risk and context
What may change the read
Base framework for context and outcome tracking. These are not trading instructions.
Tracking results
Observed daily-bar ranges are retrospective measurements, not targets, stops, or trading instructions.
Tryding Review
Five AI analytical agents reading the same evidence; disagreement stays visible.
“The day comes first. The sealed breadth cut shows 87 advancers against 213 decliners across 300 fresh quotes, with net breadth at minus 42 percent. Oil above $100 and the geopolitical shock create a defensive backdrop, so a headline move is not enough.”
I am comfortable calling SIG a Try of the Day provisionally. The mechanism, participation and current structure support the first checkpoint. The unresolved fifteen-session path belongs in the thesis and falsifier, not in a fabricated certainty.
“Agreed. That backdrop does not erase idiosyncratic catalysts, but it raises the standard. We need a concrete mechanism and evidence that the tape is responding to that mechanism rather than merely echoing the market.”
SIG therefore beats YQ and ODD on bounded continuation. YQ has a strong current revenue and margin comparison but sits 19.22 percent above VWAP with RSI at 82.81. ODD has a real recovery question, yet current revenue was reported down 25 percent and price was below VWAP.
Broader Market Context
September 9 was shaped by an oil-and-rates shock: oil moved above $100 amid escalating Gulf conflict, Treasury yields pressured equities, and the sealed intraday breadth cut showed 87 advancers versus 213 decliners across 300 fresh quotes. The wider lesson is that strong company-specific reactions must be read against a hostile market regime. No current bounded social-media thread added usable public context.
The session had a defensive macro character rather than a single clean equity trend. Public reporting described oil moving above $100 as Middle East attacks threatened supply routes, while rising Treasury yields weighed on Wall Street. European equities weakened and Asian markets were mixed. The sealed market cut added a participation warning: 87 advancers and 213 decliners across 300 fresh quotes, for net breadth of -42.0%; the end-of-day breadth layer was unavailable. That combination matters because it separates a company event from the market environment around it. Energy-related strength could coexist with pressure on broad equity participation, and technology or earnings optimism did not erase the inflation and rates problem. The market was therefore asking two questions at once: whether a company-specific catalyst was real, and whether the wider tape would allow that catalyst to persist. The room returned to SIG as a useful example of that tension. Its sealed earnings mechanism and above-VWAP reaction remain the accepted provisional decision, but the broader day adds context rather than permission: a strong event is not immune to oil, yields or deteriorating breadth. The prepared quarter’s operating-cash-flow figure remains tied to its stated period, and unavailable ML outputs remain unavailable rather than silently becoming a forecast. The public context supports a cautious reading of persistence without changing the sealed decision.
Sources consulted: Reuters
Coffee conversation
“The market arrived with oil above $100 and Treasury yields pressing on equities. That is not a background wallpaper; it is the room’s lighting, and unfortunately it is fluorescent.”
“Geopolitics is a catalyst only until it becomes weather. Once it becomes weather, every company story has to explain why it can keep raining everywhere else and still grow in one particular building.”
“And weather systems do not care about a beautiful EBITDA bridge. The sealed breadth cut was 87 advancers against 213 decliners across 300 fresh quotes. That is a market saying, rather plainly, that enthusiasm is being rationed.”
“The index picture was not a neat collapse, though. Energy held up better while other groups absorbed the pressure. It was a split screen: one side pricing scarcity, the other side pricing the bill for scarcity.”
“Small correction: 300 fresh quotes are a useful participation sample, not a census of the planet. The correct inference is defensive breadth at that cut, not universal market failure.”
“Yes. Breadth is a warning light, not a prophecy. But it changes the burden of proof for every stock that wants to turn a one-day reaction into a durable story.”
“That is why the SIG case remains interesting without becoming magical. The event is company-specific and the tape responded, but no earnings beat receives diplomatic immunity from oil, rates and a hostile index.”
“Exactly. The public mistake would be to hear “above VWAP” and translate it into “safe.” Above VWAP is a piece of structure. It is not a signed treaty with the next fifteen sessions.”
“The tape can lend a thesis credibility, but it cannot lend it immunity. If breadth keeps deteriorating, individual strength starts to look borrowed. Sometimes the market sends the invoice later.”
“And the data boundaries stay boring but important. The EOD breadth layer was unavailable, and the model questions were unavailable. An empty model field is not a bearish score, just as an unavailable EOD layer is not a hidden conclusion.”
“The alternatives tell the same story in different accents. Some had cleaner operating bases, some cleaner charts, some louder current events. None could be separated from the regime risk by simply turning up the volume on its headline.”
“That is the useful tension: broad context should calibrate the claim, not erase the company evidence. A defensive day can contain a valid idiosyncratic reaction. It just makes the word “persistent” more expensive.”
“And if the next check fails, the market will not care that the original thesis was elegantly written. Oil, yields and liquidity are very rude editors.”
“The day leaves us with a split question rather than a tidy answer: can a specific earnings reaction keep its shape while the broad tape keeps losing breadth? That is more honest than pretending the index supplied a verdict.”
“And no fresh social-media thread is needed to decorate that uncertainty. The public record already gives us the useful contradiction: real company events can coexist with a market regime that refuses to make continuation easy.”
Timeline
SIG's tracked gain improved 0.41 points to +4.20% as the latest capture rose 3.07% to $102.94 on 1.32 times average volume. The earnings-linked repricing still has relative strength behind it, but price slipped below VWAP with decelerating participation near the 52-week high and no confirmed structure; the event case survives, while durable continuation remains unproven.
SIG has repaired the break that put its earnings-backed thesis under pressure: the tracked return improved 3.73 points from -2.62% at the last panel note to +1.11%, while price moved above VWAP and into the upper part of the range. The repair is not yet durable evidence—volume was 0.72 times average, no structure is confirmed, and the stock remains extended—so the event case survives while continuation stays conditional.
SIG tracked return fell 6.35 points to -2.62% since the last public note. The latest capture dropped 5.75% to USD 96.59, 2.09% below VWAP near the bottom of its range on 0.44 times average volume, with no confirmed structure despite decelerating participation. The earnings-backed case remains specific and Consumer Cyclical-relative strength is still positive, but the opening repricing has lost its short-term hold.
SIG's tracked return rose from 1.74% to 3.73% since the last public note as the latest capture gained 23.96% to $102.48 on 5.88x average volume and held above VWAP near the upper part of its range. The earnings-backed mechanism now has stronger immediate support, but the move is extended near the 52-week high and still lacks confirmed structure, so continuation remains conditional.
Panel thesis: Signet’s same-day profit beat, raised full-year profit outlook and $125 million buyback are tied to an observable repricing that held above the 97.58 VWAP in a weak market; the current S0-S15 thesis is that the earnings-backed mechanism can persist if the event structure and raised outlook hold. Invalidation boundary: A sustained break below the 97.58 VWAP and the earnings-day range, followed by failure of the raised profit outlook, would falsify continuation.
Panel comparison
Selected candidate versus the alternatives retained from the panel comparison.
Latest display-only snapshot · Sep 16, 2026 · 18:22 NYSE
Since base +4.20% · Today +3.07% · Since prior +0.42% · Vs S&P 500 +3.52% · Vs Nasdaq 100 +3.04% · Vs Russell 2000 +3.47% · Relative volume 1.32 · RSI 72.59 · EMA 96.25 > 91.91 > 89.85 · VWAP below -0.54% · 52-week high 93.40% · As of Sep 16, 2026 · 16:00 NYSE
Since base +4.22% · Today -1.16% · Since prior 0.00% · Vs S&P 500 -0.71% · Vs Nasdaq 100 -1.18% · Vs Russell 2000 -0.76% · Relative volume 1.28 · RSI 53.11 · EMA 45.08 > 45.49 > 46.62 · VWAP below · 52-week high 77.58% · As of Sep 9, 2026 · 17:15 NYSE
Since base -0.54% · Today -0.34% · Since prior 0.00% · Vs S&P 500 +0.10% · Vs Nasdaq 100 -0.37% · Vs Russell 2000 +0.06% · Relative volume 1.74 · RSI 72.4 · EMA 12.83 > 12.27 > 11.75 · VWAP above · 52-week high 99.83% · As of Sep 9, 2026 · 16:52 NYSE
Since base -7.99% · Today -0.82% · Since prior 0.00% · Vs S&P 500 -0.37% · Vs Nasdaq 100 -0.84% · Vs Russell 2000 -0.42% · Relative volume 1.23 · RSI 66.02 · EMA 10.97 > 10.94 > 10.83 · VWAP above · 52-week high 93.04% · As of Sep 9, 2026 · 16:41 NYSE
Since base -3.17% · Today -6.79% · Since prior 0.00% · Vs S&P 500 -6.34% · Vs Nasdaq 100 -6.81% · Vs Russell 2000 -6.39% · Relative volume 10.63 · RSI 82.81 · EMA 3.04 > 2.63 > 2.42 · VWAP above · 52-week high 68.20% · As of Sep 9, 2026 · 17:16 NYSE
Benchmarks
Today -0.45% · previous regular close · As of Sep 16, 2026 · 18:21 NYSE
Today +0.03% · previous regular close · As of Sep 16, 2026 · 18:21 NYSE
Today -0.40% · previous regular close · As of Sep 16, 2026 · 18:21 NYSE
Company dossier
History, curiosities & sources

Selected facts and links behind the public profile.
Company description
Signet Jewelers Limited operates as a diamond jewelry retailer in the United States, Canada, the United Kingdom, and Republic of Irland. It operates through three segments: North America, International, and other. The North America segment operates jewelry stores in malls, mall-based kiosks, and off-mall locations in the United States and Canada primarily under the Kay, Zales, Jared Jewelers, Diamonds Direct, Banter by Piercing Pagoda, Peoples Jewellers, and Rocksbox brands, as well as operates online through its digital brands, James Allen and Blue Nile. The International segment operates stores in shopping malls, off-mall locations, and online primarily under the H.Samuel and Ernest Jones brands in the United Kingdom and the Republic of Ireland. The Other segment engages in the purchase and conversion of rough diamonds to polished stones, as well as offers diamond polishing services. Signet Jewelers Limited was founded in 1862 and is based in Hamilton, Bermuda.