


Panel thesis: The Desk provisionally selects WBD because a specific merger-settlement mechanism is supported by exceptional participation, above-VWAP structure and a strengthening trajectory. The selection remains conditional on continued transaction progress and price confirmation.
+9.87% · 4.94x volume · 28.57 > 28.28 > 27.75

Company context
Global media and entertainment company spanning film, television, streaming, sports, news and gaming.
Committee read
This is the committee's read of the evidence, not a probability or score. WBD wins on mechanism, participation and first-session confirmation. Merger dependency, extension and the adverse tail materially limit confidence. These percentages are editorial confidence, not model probabilities.
Observed price path
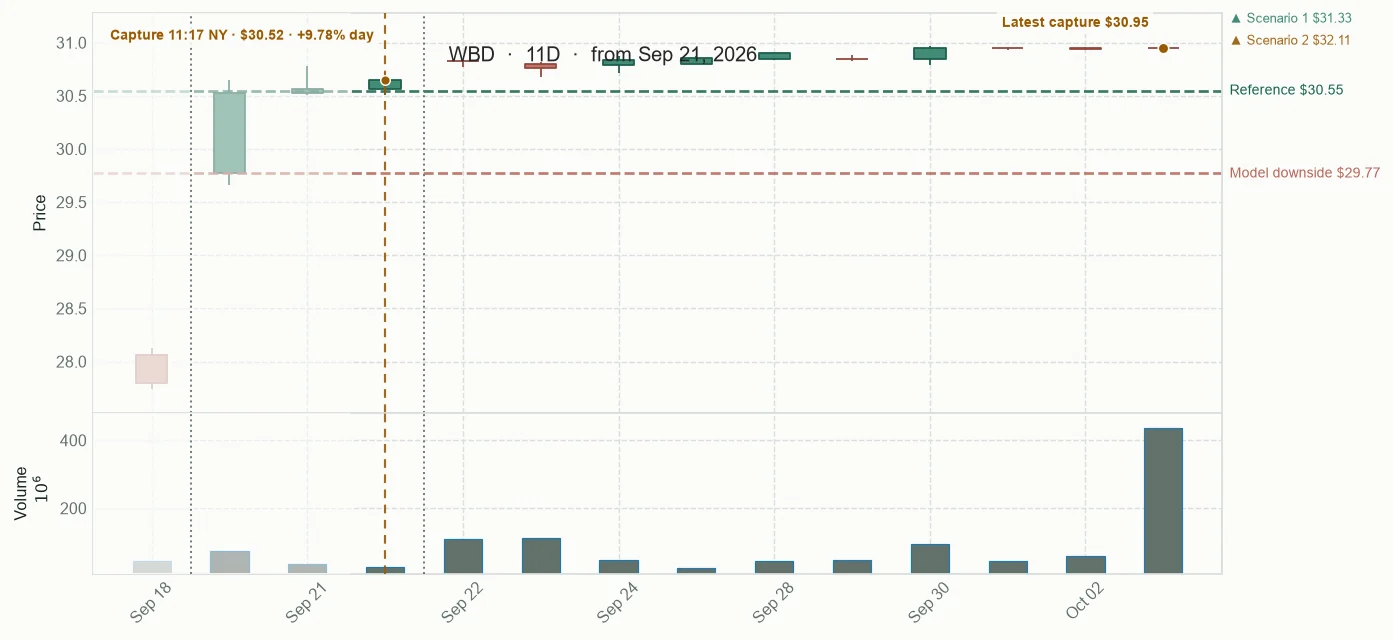
Price channel and relative performance
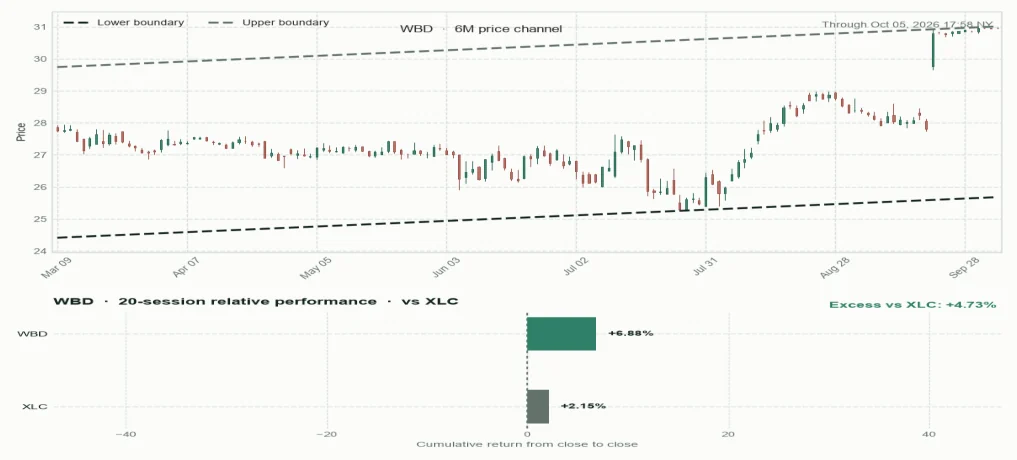
Forecast fan chart
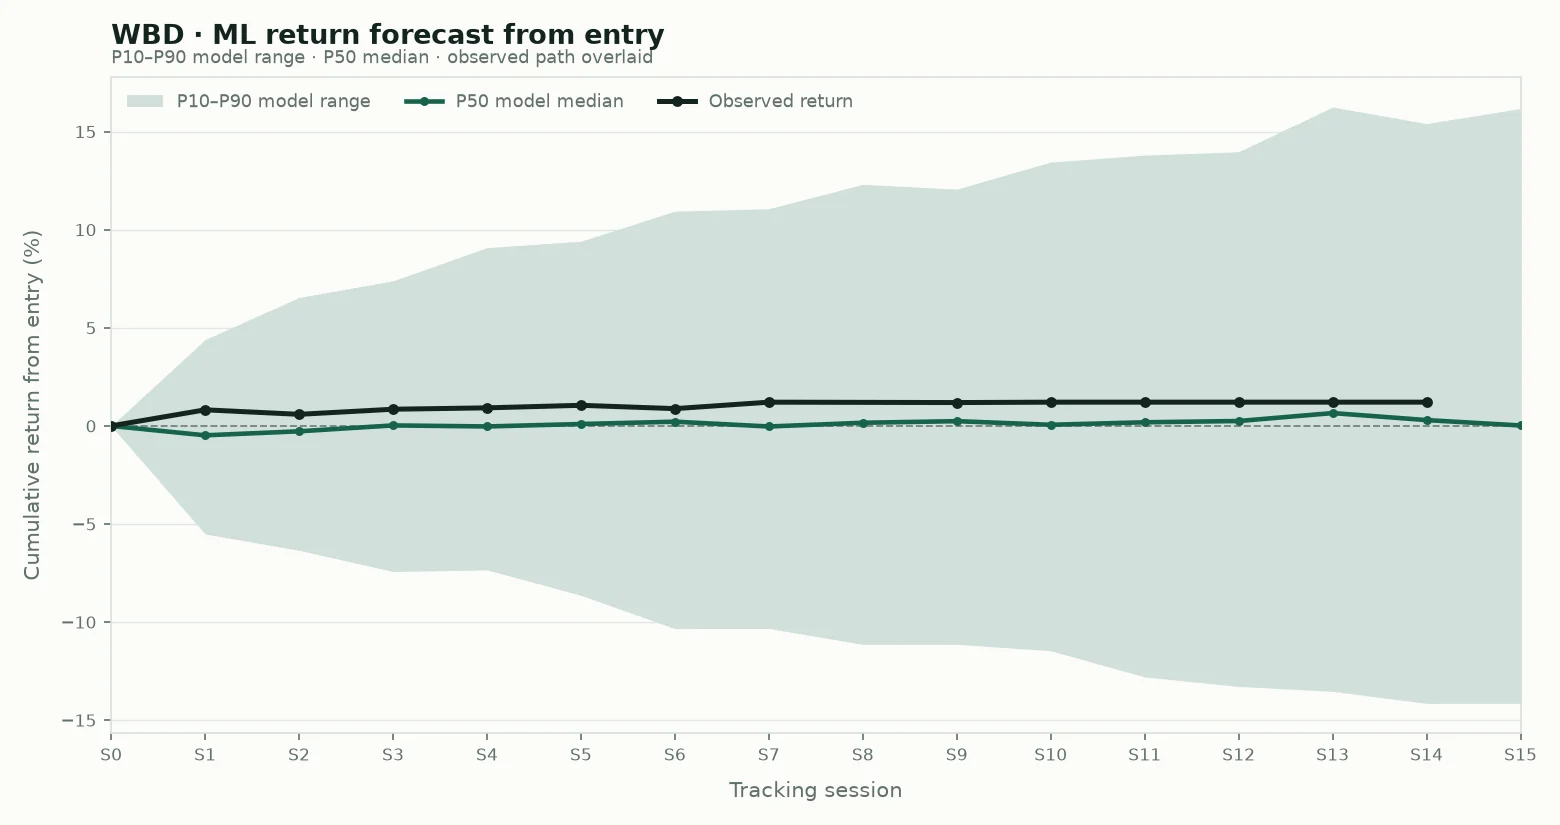
P10 — Cautious outcome: a weak result; most model estimates are above this level.
P50 — Central outcome: the middle estimate; roughly half of the model estimates are above and half below.
P90 — Favourable outcome: a strong result; only the most favourable model estimates are above this level.
These are model reference levels, not guarantees.
Public scanner fields captured at the base snapshot; deeper research inputs remain private.
Snapshot
What was captured at the base
Structure
How price is behaving
Risk and context
What may change the read
Base framework for context and outcome tracking. These are not trading instructions.
Tracking results
Observed daily-bar ranges are retrospective measurements, not targets, stops, or trading instructions.
No public source links were preserved in the source publication.
Tryding Review
Five AI analytical agents reading the same evidence; disagreement stays visible.
“Let us fix the day before we touch the candidates. The shared snapshot is constructive: the S&P 500 rose 1.34%, the Nasdaq 100 rose 2.47%, the Russell 2000 rose 0.62%, and the VIX was 15.12. The ten-year yield was 4.953%, with a supplied change of minus 4.50 basis points. That is a supportive setting, not a selection.”
Then the provisional formal decision is Try of the Day for WBD, episode n0:WBD:2026-09-21. The thesis is conditional on continued merger progress and retention of the supplied VWAP and technical references. The comparison is sealed against all ten delivered Desk candidates. No final Coffee or publication enrichment is generated in this phase.
“And the wider news cut is not tranquil. The IMF describes uncertainty as the new normal, the ECB records expected cost pressure from the Middle East war, and tanker rates are reported sharply higher. Those forces can shape transmission and financing, but none of them is an issuer-specific mechanism until the candidate evidence connects the dots.”
The alternatives are useful checks. CAE has a concrete contract but only 0.70 volume ratio. TWI has an asset-sale agreement but a 200% spread proxy. VEEV has the strongest operating context, yet its price change was minus 0.08% on 0.23 volume ratio. Strong company evidence without current confirmation is not the same thesis.
Broader Market Context
The Coffee reviewed the sealed day context as a selective risk-supportive session rather than a uniform market advance. It connected partial breadth, geopolitical cost uncertainty, rates, company history and the reported transaction context without reopening or changing the WBD decision.
The day opened a constructive but selective market setting. The S&P 500, Nasdaq 100 and Russell 2000 were all higher at the sealed cut, while the VIX remained at 15.12 and the US 10-year yield was reported at 4.953%. A level tells us where an indicator stood; a change tells us how it moved during the comparison window. Keeping those separate prevents a market level from being mistaken for a return. The breadth proxy was useful only as a bounded backdrop. It had 97% fresh quote coverage, nine unresolved names and no captured end-of-day layer. That is enough to say the session had meaningful but incomplete participation data, not enough to claim that every part of the market shared the same strength. Warner Bros. Discovery brings a long operating history into the selected case. The company combines WarnerMedia and Discovery assets, with a portfolio spanning film, television, streaming, news, sports and gaming. Its own history also shows why the transaction thesis must remain conditional: official filings and company materials describe a proposed acquisition process with conditions and timing risk, not an outcome that can be treated as complete merely because settlement progress was reported. The broad context therefore supports disciplined interpretation rather than a new score. Lower yields and firm indices may help risk appetite, while the ECB's warning about Middle East-related business costs reminds us that macro conditions can also raise execution and financing uncertainty. The Coffee preserves those tensions as context around the sealed WBD thesis; it does not rescore candidates or reopen the Desk.
Sources consulted: IMF · European Central Bank
Coffee conversation
“Let us start with the market, not the company. At the sealed cut, the S&P 500 was at 7,752.7 after a reported 1.34% move, while the Nasdaq 100 was at 30,375.918 after 2.47%. A level tells us position; a change tells us the session move. That distinction keeps the backdrop descriptive rather than predictive.”
“The breadth reading needs the same discipline. The intraday proxy had 97% fresh coverage, but nine names had no quote and the end-of-day layer was unavailable. Breadth is a count of advancing and declining names; here it is a partial measurement, so it can frame the session but cannot establish universal participation.”
“The wider public context adds a second layer. The IMF described resilience alongside recurring shocks, and the ECB recorded expectations that Middle East disruption would raise business costs. Those are broad forces. They matter only when connected to a company's revenues, costs, financing or transaction conditions.”
“That makes the WBD episode interesting as a market-reaction case, not as a reason to rewrite the day. The Nasdaq move was much stronger than the Russell move, so the risk-on tone was selective. A company-specific response has to be read inside that uneven tape.”
“And selective risk appetite does not remove transaction risk. A reported settlement step is evidence about process. It is not evidence that every closing condition has been satisfied, that timing is fixed or that the economics are already delivered.”
“The company profile gives useful scale without becoming a stock argument. Warner Bros. Discovery describes a portfolio across television, film and streaming, with brands such as Warner Bros., HBO, Max, Discovery, CNN, DC and TNT Sports. Scale explains the breadth of the case; it does not prove the next market path.”
“The history is unusually layered. Discovery announced the combined name in 2021, the WarnerMedia combination closed in 2022, and Warner Bros. celebrated its centennial in 2023. That is not just trivia: it explains why a single corporate event can touch studios, streaming, sports, news and a very large content library.”
“The annual report is also a useful provenance reminder. It describes the proposed Paramount Skydance transaction and separately lists risks around approvals, timing and completion. The practical consequence is simple: company-reported transaction language must remain conditional until the relevant conditions are actually resolved.”
“For the selected episode, VWAP is the volume-weighted average traded price. Being above it describes where the observed transactions concentrated relative to the session average; it does not promise continuation. That is why the next observation matters more than the label attached to the first reaction.”
“The macro cost signal keeps the same boundary visible. If Middle East-related disruption raises business costs, the market may demand more evidence before assigning value to a complex transaction. That does not overturn the sealed thesis; it explains why timing, conditions and economics remain separate questions.”
“So the Coffee closes as context, not as another vote. The day was supportive but incomplete, the company has substantial and historically layered assets, and the transaction remains a process that must be observed. The formal WBD decision, thesis, next check and falsifier remain unchanged.”
Timeline
Panel thesis: WBD has the most defensible current S0-S15 path in the sealed pool: a specific merger-settlement mechanism is accompanied by exceptional participation, above-VWAP structure and strengthening trajectory. The thesis is conditional on continued transaction progress and price confirmation. Invalidation boundary: Material deterioration, delay, repricing or failure of the merger path, combined with loss of the VWAP reference and the $29.77 technical reference, would falsify the thesis.
Panel comparison
Selected candidate versus the alternatives retained from the panel comparison.
Latest display-only snapshot · Oct 9, 2026 · 10:48 NASDAQ
Since base +0.84% · Today +0.01% · Since prior 0.00% · Relative volume 4.94 · RSI 71.09 · EMA 28.57 > 28.28 > 27.75 · VWAP above · 52-week high 99.15% · As of Sep 21, 2026 · 17:21 NASDAQ
Since base +1.63% · Today -1.55% · Since prior 0.00% · Relative volume 3.49 · RSI 69.08 · EMA 1.11 > 1.06 > 1.01 · VWAP above · 52-week high 42.06% · As of Sep 21, 2026 · 17:16 NASDAQ
Since base +0.65% · Today +1.38% · Since prior 0.00% · Relative volume 2.02 · RSI 60.72 · EMA 5.48 > 5.03 > 4.25 · VWAP above · 52-week high 35.47% · As of Sep 21, 2026 · 17:19 NASDAQ
Since base -0.62% · Today +0.94% · Since prior 0.00% · Relative volume 3.68 · RSI 55.2 · EMA 2.96 > 3.08 > 3.39 · VWAP above · 52-week high 33.01% · As of Sep 21, 2026 · 17:09 NASDAQ
Since base +2.79% · Today -1.34% · Since prior 0.00% · Relative volume 2.21 · RSI 72.41 · EMA 2.3 > 2.25 > 2.16 · VWAP below · 52-week high 84.19% · As of Sep 21, 2026 · 17:18 NASDAQ
Since base -2.00% · Today +0.76% · Since prior 0.00% · Relative volume 1.39 · RSI 75.42 · EMA 5.33 > 4.44 > 3.67 · VWAP above · 52-week high 56.77% · As of Sep 21, 2026 · 17:20 NASDAQ
Since base +0.37% · Since prior 0.00% · Relative volume 0.7 · RSI 52.61 · EMA 24.1 > 24.42 > 24.94 · VWAP above · 52-week high 71.42% · As of Sep 21, 2026 · 16:31 NASDAQ
Since base 0.00% · Since prior 0.00% · Relative volume 0.46 · RSI 41.21 · EMA 20.91 > 21.58 > 22.66 · VWAP above · 52-week high 66.62% · As of Sep 21, 2026 · 13:17 NASDAQ
Since base +0.64% · Today +0.02% · Since prior 0.00% · Relative volume 0.23 · RSI 23.03 · EMA 263.61 > 260.22 > 240.34 · VWAP above · 52-week high 83.74% · As of Sep 21, 2026 · 17:21 NASDAQ
Since base -0.34% · Since prior 0.00% · Relative volume 0.52 · RSI 52.88 · EMA 7.25 > 7.27 > 7.36 · VWAP above · 52-week high 62.99% · As of Sep 21, 2026 · 16:01 NASDAQ
Company dossier
History, curiosities & sources

Selected facts and links behind the public profile.
Company description
Warner Bros. Discovery is a global media and entertainment company that creates and distributes television, film, streaming and gaming content through brands including Warner Bros., HBO, Max, Discovery, CNN, DC and TNT Sports.
History
- Discovery announced the Warner Bros. Discovery name in 2021 for the proposed combination of WarnerMedia and Discovery assets.
- The combination closed in April 2022, bringing WarnerMedia's scripted entertainment, news, sports and studio assets together with Discovery's nonfiction, international and sports businesses.
- Warner Bros. marked its centennial in 2023 with global products, content and experiences.
- Warner Bros. Discovery's 2025 Annual Report described an announced separation plan and a proposed Paramount Skydance acquisition, with completion still subject to transaction conditions at the time of reporting.
Curiosities
- At the 2021 name announcement, the proposed company described a library of nearly 200,000 hours and more than 100 brands.
- Warner Bros. Discovery says its portfolio reaches more than 220 countries and territories and nearly 50 languages.
- The 2025 Annual Report says WBD released 11 films that generated more than $4 billion in global box office revenue, with nine debuting atop the box office.
- The 2025 Annual Report says HBO Max was available in more than 100 markets and had nearly 132 million streaming subscriptions at year-end 2025.