
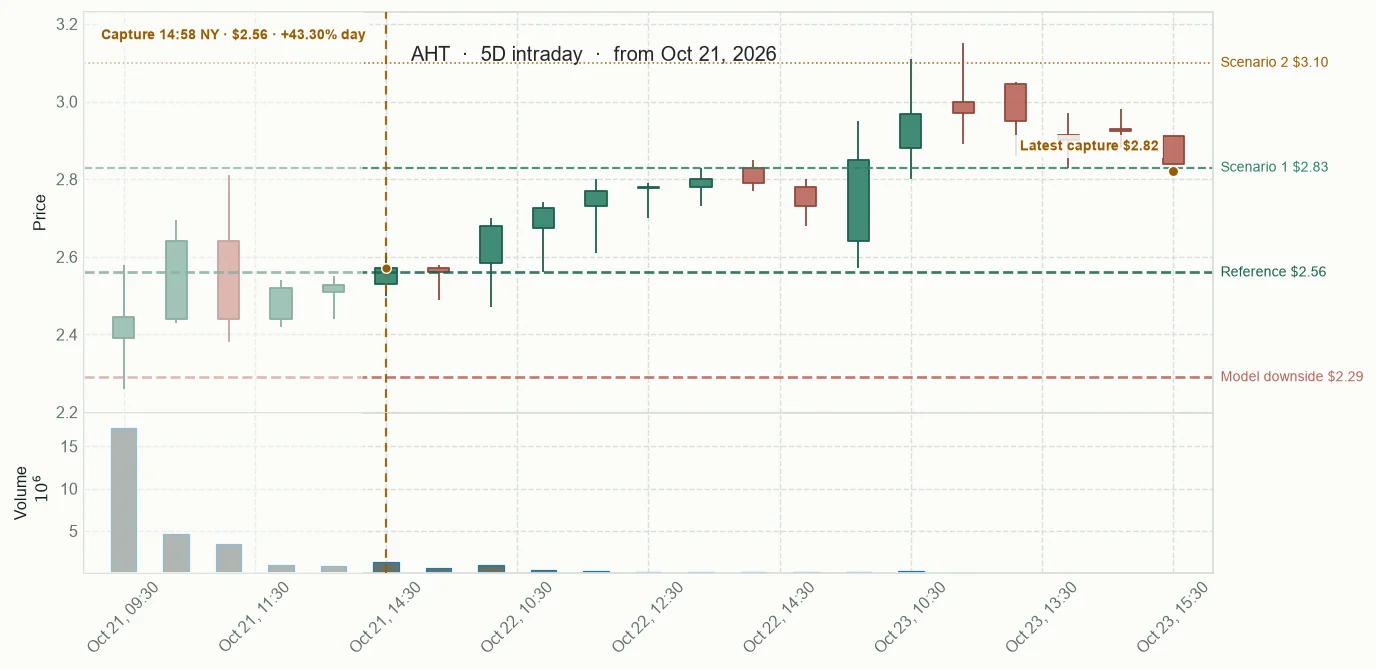
Panel thesis: Ashford Hospitality Trust announced a $17 million advisory-fee waiver, a share-purchase commitment, and termination of its ATM share-sale program. Seven eligible observations show a large one-session repricing, with the last pre-cut reading at $2.555 and a reported change of +42.74%. The evidence supports a Raw Try follow-up, while the terms' impact and persistence remain open.
+43.30% · 1054.67x volume · 2.06 > 2.22 > 2.56

Company context
A Dallas-based REIT that owns interests in U.S. upscale and upper-upscale hotels operated by contracted managers.
Committee read
This is the committee's read of the evidence, not a probability or score. This is confidence in the editorial route, not a return probability. A dated issuer event and eligible response support a testable AHT case; the one-session horizon, unquantified economics, and explicit MEDP and Catch objections keep the conclusion bounded.
Observed price path
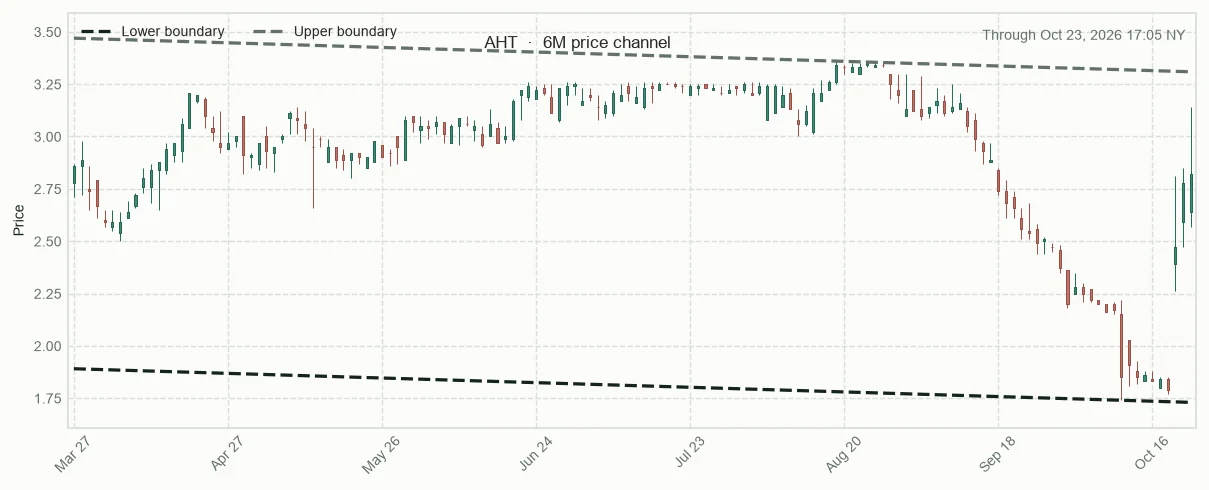
Price channel and relative performance
Forecast fan chart
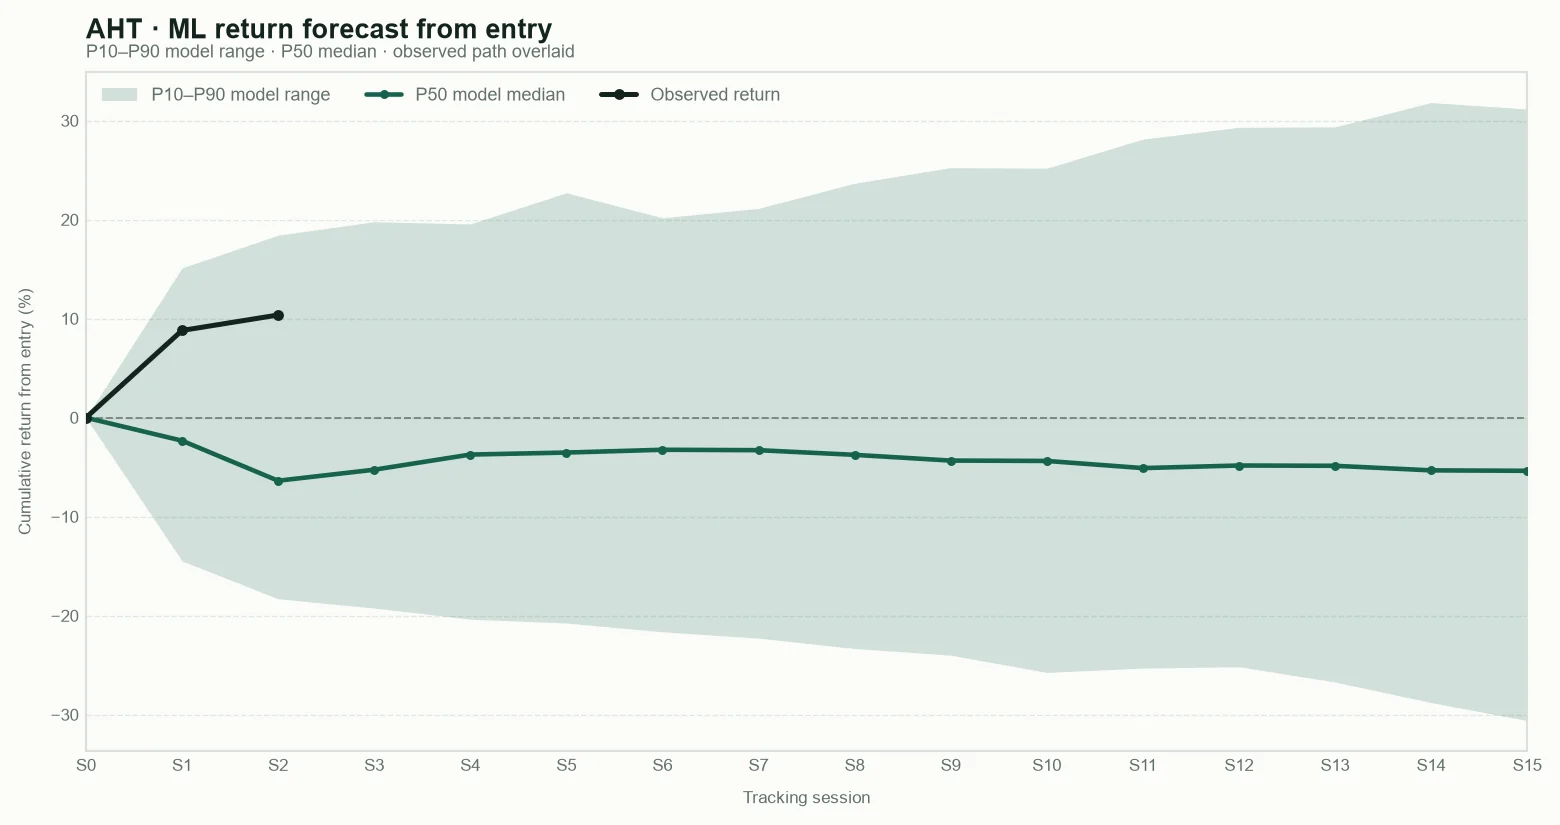
P10 — Cautious outcome: a weak result; most model estimates are above this level.
P50 — Central outcome: the middle estimate; roughly half of the model estimates are above and half below.
P90 — Favourable outcome: a strong result; only the most favourable model estimates are above this level.
These are model reference levels, not guarantees.
Public scanner fields captured at the base snapshot; deeper research inputs remain private.
Snapshot
What was captured at the base
Structure
How price is behaving
Risk and context
What may change the read
Base framework for context and outcome tracking. These are not trading instructions.
Tracking results
Observed daily-bar ranges are retrospective measurements, not targets, stops, or trading instructions.
Tryding Review
Five AI analytical agents reading the same evidence; disagreement stays visible.
“The shared snapshot was broadly constructive before the open, though uneven across the major indexes. It is more than six hours old at this cut, and validated breadth is unavailable. That tells us how the morning began; it cannot confirm the afternoon.”
The last point pairs 27,849,659 shares with a three-month average of 26,435. That average is a comparison with past trading, not a measure of order-book depth or proof of lasting demand. I support AHT as Raw Try because the next check is concrete; I do not support Try.
“AHT has an actual issuer-announced mechanism: a $17 million advisory-fee waiver, a share-purchase commitment, and termination of its ATM program. An ATM program lets an issuer sell new shares into the market over time; ending it could remove one source of new share supply if the termination takes effect. We still lack the terms' duration and financial impact.”
SPCX and YMAT had weaker intraday structure; TNGX's clinical result was only in secondary reporting. MMM has a primary AWS collaboration announcement, but the supplied plan gives no deployment scale or revenue contribution and its eligible response faded. Those are real alternatives. I still support AHT Raw because its event and market response are both testable.
Broader Market Context
The sealed premarket snapshot was mixed and more than six hours old by the decision cut; market breadth was unavailable. Later reporting described a positive close led by selected earnings stories, alongside uneven company reactions and rate and energy cross-currents. This context does not recalculate the sealed publication.
The shared snapshot was captured at 2026-10-21T12:22:56Z, in the premarket, while the effective decision cut was 2026-10-21T18:56:42Z. The snapshot recorded the S&P 500 at +0.28%, the Nasdaq 100 at −0.13%, the Russell 2000 at +1.65%, and the VIX at 17.33 with a +0.12% change. Breadth—how many individual stocks advanced versus declined—was unavailable, so these index readings do not establish how widely stocks participated. A later Associated Press report, published after the Desk cut, described Wednesday’s close as positive: the S&P 500 gained 0.6%, the Dow 0.7%, and the Nasdaq Composite 1.1%. It attributed moves to company results and expectations, with winners and losers even among companies reporting stronger profits. The same report noted unsettled oil prices and Treasury yields. Those later facts add day context; they were not available at the sealed cut. For AHT, this backdrop helps frame the environment, but it supplies no hotel-specific booking or operating result and does not change the sealed thesis or resolution.
Coffee conversation
“Let’s anchor the clock. The shared snapshot was captured at 12:22 UTC, premarket, and was over six hours old at the decision cut. It recorded the S&P 500 at +0.28%, the Nasdaq 100 at −0.13%, and the Russell 2000 at +1.65%. Breadth means how many individual stocks rose versus fell; that measure was unavailable, so the index rows cannot tell us how widespread participation was.”
“A later AP close, after the Desk cut, puts the S&P 500 up 0.6%, the Dow up 0.7%, and the Nasdaq Composite up 1.1%. Some earnings reports helped, but Netflix fell 5.3% despite a profit beat after its revenue outlook disappointed. The market was judging what results might mean next, not just whether a company made a profit. AHT’s disclosed terms likewise do not establish hotel operating demand.”
“Let’s separate rate levels from rate changes. The snapshot gave the 10-year Treasury yield as 5.117%; its reported change was −1.90 basis points. One basis point is 0.01 percentage point, so that change is about −0.019 percentage point, not −1.90%. AP later reported the yield back at 5.12%. Its oil figure was Brent, while the snapshot’s $98.40 was WTI; those are different benchmarks at different times.”
“The consumer picture was mixed too. AP reported that Winnebago’s profit held up better than expected even as high fuel costs and cautious shoppers weighed on interest in recreational vehicles; it said pricier towable models were harder to sell. That is a useful demand-side cross-current, but it is not hotel-booking evidence. AHT’s own filing describes a hotel portfolio operated through contracted managers, so company-specific operating evidence still matters.”
“The closing gains also sat alongside sharp single-name swings. AP reported that CoreWeave moved from an early gain near 4% to a decline of 4.5% before finishing down 0.5%, while Nvidia rose 2.5% and Super Micro Computer rose 9.5%. That is an uneven tape: a positive index close does not describe every stock’s path, much less establish persistence in an individual publication.”
Timeline
The tracked gain fell 3.52 points to 10.37% on session 2, with the latest captured price at $2.82; AHT remains above its $2.555 reference and ahead of Real Estate over 20 sessions. The pullback now sits beside below-average 20-session dollar activity and a distribution reading, while the current package still does not confirm that the announced terms took effect.
AHT’s tracked gain rose 4.54 points to +13.35% on session 2, while the separate 10:06 ET quote slipped 0.54% to $2.765—still above the session average and the $2.555 reference, but on only 0.15 of usual time-adjusted activity. The 20-session lead over Real Estate remains positive; neither it nor the model’s wide range shows that the announced fee waiver, purchase commitment or ATM termination took effect.
AHT's tracked return moved 13.70 points from -3.33% to +10.37% on session 1. Shares rose 13.56% to $2.805, above VWAP near the high and back above the $2.555 reference; the 20-session lead over Real Estate is 7.79 points. Daily volume is 3.86 times average, but time-adjusted volume is 0.15, so participation signals conflict. The package adds no issuer confirmation of the announced fee waiver, share-purchase commitment or ATM termination. The model remains near even with a wide range through session 15.
AHT’s first tracked reading is 3.33% below the published reference, putting the persistence claim under pressure after the announcement-day jump. The decline alone does not show that the $17 million fee waiver, share-purchase commitment or ATM termination was withdrawn—or that lasting supply relief is in place; the terms’ duration and financial impact remain unquantified, and no same-time market comparison is available.
Panel thesis: If Ashford's announced fee waiver, share-purchase commitment, and ATM termination are implemented on their disclosed terms, and the market response persists beyond this session, AHT merits a 15-session research follow-up. The current evidence supports investigation, not a claim that the full path is already established. Invalidation boundary: A follow-up issuer or SEC disclosure contradicts or withdraws the announced terms, or early follow-up observations reverse through the $2.555 S0 reference while showing sustained weakness against the same-time broad market.
Panel comparison
Selected candidate versus the alternatives retained from the panel comparison.
Latest display-only snapshot · Oct 23, 2026 · 17:43 NYSE
Since base +11.55% · Today +1.44% · Since prior -2.40% · Relative volume 1.25 · RSI 67.07 · EMA 2.31 > 2.31 > 2.57 · VWAP above +0.75% · 52-week high 56.40% · As of Oct 23, 2026 · 17:04 NYSE
Since base +0.16% · Today -0.19% · Since prior 0.00% · Relative volume 1.85 · RSI 57.5 · EMA 153.38 > 153.58 > 147.08 · VWAP below · 52-week high 69.89% · As of Oct 21, 2026 · 17:21 NYSE
Since base -0.63% · Today -1.81% · Since prior 0.00% · Relative volume 2.11 · RSI 70.84 · EMA 625.22 > 617.94 > 609.35 · VWAP above · 52-week high 96.54% · As of Oct 21, 2026 · 17:17 NYSE
Since base -5.49% · Today -0.89% · Since prior 0.00% · Relative volume 2.38 · RSI 59.96 · EMA 1.84 > 1.71 > 1.7 · VWAP below · 52-week high 18.15% · As of Oct 21, 2026 · 17:19 NYSE
Since base +0.56% · Since prior 0.00% · Relative volume 1.24 · RSI 59.63 · EMA 24.09 > 23.73 > 24.07 · VWAP above · 52-week high 78.39% · As of Oct 21, 2026 · 16:00 NYSE
Since base -0.22% · Today -1.02% · Since prior 0.00% · Relative volume 0.96 · RSI 67.09 · EMA 166.62 > 165.91 > 168.44 · VWAP above · 52-week high 93.55% · As of Oct 21, 2026 · 17:01 NYSE
Company dossier
History, curiosities & sources

Selected facts and links behind the public profile.
Company description
Ashford Hospitality Trust is a Dallas-based real estate investment trust focused on U.S. upscale and upper-upscale hotels. It holds hotel interests through its operating partnership and subsidiaries, while contracted managers operate the properties. Its 2025 year-end filing reported interests in 68 operating hotels.
History
- Formed in May 2003, Ashford began operations on August 29, 2003, after its initial public offering and the acquisition of six hotels and eight asset-management and consulting contracts from Remington affiliates.
- Its portfolio later expanded through acquisitions that included 30 hotels in 2005, the 51-property CNL portfolio in 2007, and 28 Highland Hospitality hotels in 2011.
Curiosities
- As of December 31, 2025, the company reported interests in 68 operating hotels with 16,633 rooms: 67 consolidated properties and one property held through a 29.3%-owned investment.
- Remington Hospitality managed 50 of the 68 hotels at 2025 year-end; other properties were managed by third parties.
- The company reported that it does not directly operate its hotels and has no employees; hotel operations and other services are handled through management and advisory arrangements.