


Panel thesis: Huntington Ingalls' Q3 results, new awards and higher shipbuilding revenue outlook provide a traceable operating mechanism. Its shares gained 12.57% on 1.98x average volume, stayed above the day's volume-weighted average price and held near +12.5% across five same-day observations. The comparison favors HII for the prospective 15-session case, while its extended price and the still-unobserved follow-through remain material risks.
+12.57% · 1.98x volume · 283.63 > 277.02 > 281.46

Company context
HII builds and supports naval vessels and provides defense technologies through Newport News Shipbuilding, Ingalls Shipbuilding and Mission Technologies.
Committee read
This is the committee's read of the evidence, not a probability or score. Editorial confidence in the comparative evidence, not a forecast probability or model score. Four of five voices support Try of the Day; one explicitly prefers Raw Try because of HII's extension and the unobserved 15-session path. The downside tail and one-session horizon keep confidence bounded.
Observed price path
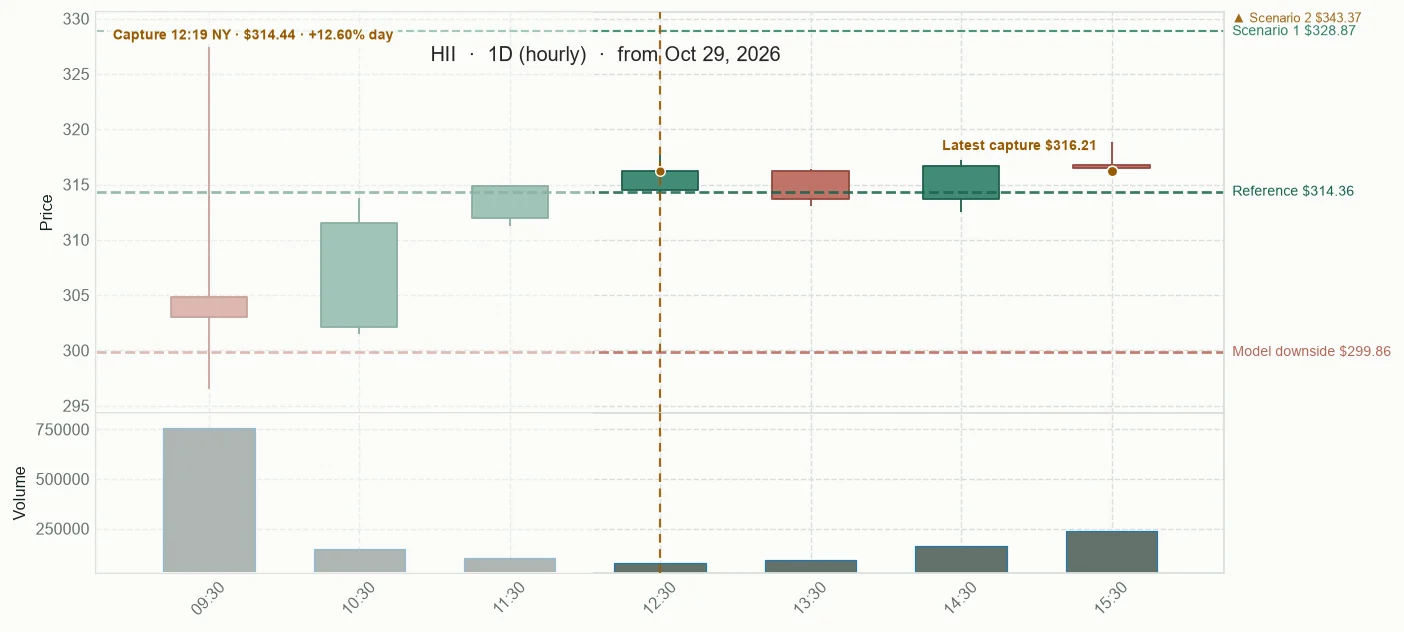
Price channel and relative performance
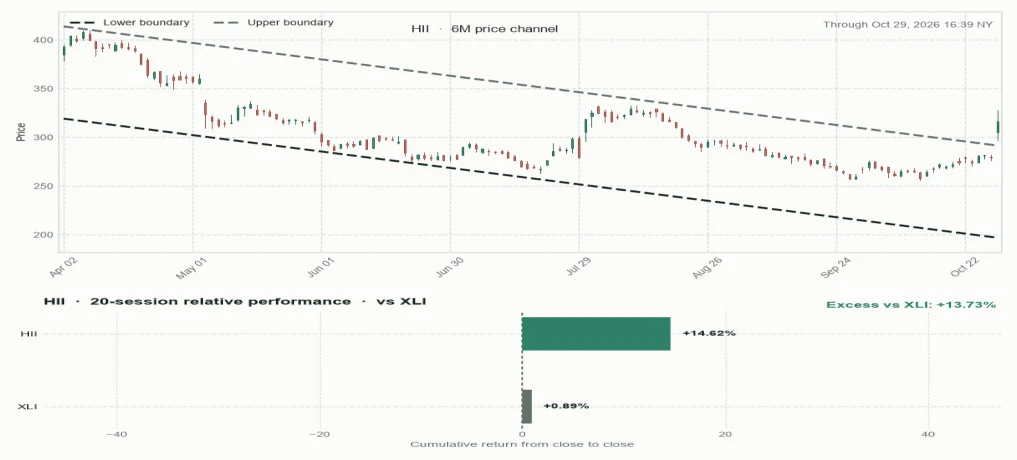
Forecast fan chart
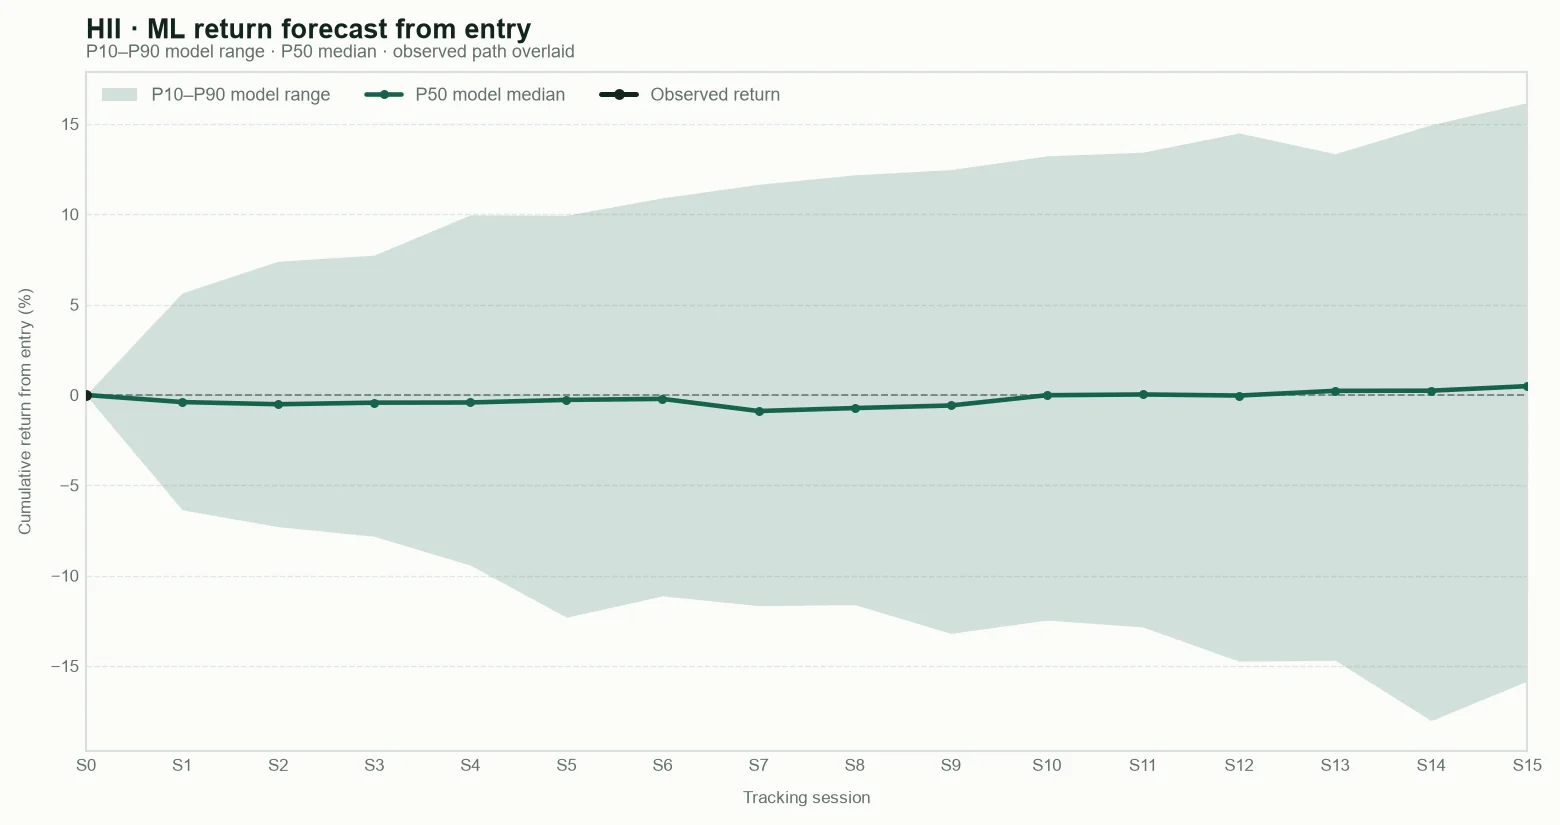
P10 — Cautious outcome: a weak result; most model estimates are above this level.
P50 — Central outcome: the middle estimate; roughly half of the model estimates are above and half below.
P90 — Favourable outcome: a strong result; only the most favourable model estimates are above this level.
These are model reference levels, not guarantees.
Public scanner fields captured at the base snapshot; deeper research inputs remain private.
Snapshot
What was captured at the base
Structure
How price is behaving
Risk and context
What may change the read
Base framework for context and outcome tracking. These are not trading instructions.
Tracking results
Observed daily-bar ranges are retrospective measurements, not targets, stops, or trading instructions.
Tryding Review
Five AI analytical agents reading the same evidence; disagreement stays visible.
“The broad tape is mixed: the S&P 500 and Nasdaq 100 were lower, while the Russell 2000 was higher. The Fed held its range, but two members preferred a 25-basis-point increase; a basis point is one hundredth of a percentage point. That makes the policy backdrop relevant, not a company-level explanation.”
Agreed. My earlier wording incorrectly tied the 51.8% H15 positive-return estimate to eight historical cases and mislabeled the historical -23.96% P10 as a modeled adverse-MAE quantile. They are separate measures: the probability is an active model estimate; the eight-case historical adverse-MAE P10 is -23.96%; and the separate modeled H15 adverse-MAE P10 is -19.57%. The eight-case historical return dispersion from -20.01% to +20.95% is another distinct measure. These samples and tails bound confidence; they do not make the probability certain or drive the selection by themselves.
“The market snapshot is from 17:55 UTC. The separate breadth proxy is earlier, from 17:35, and its end-of-day layer is missing. Breadth means how broadly stocks participate; the available proxy leaned positive, which tempers a simple risk-off reading, but it is still a 300-name intraday sample.”
The candidate comparison, HII selection and recorded four-to-one committee split remain unchanged. This correction fixes the public explanation of the ML outputs; it does not reopen candidate selection.
Broader Market Context
The day’s context was mixed: large-cap indexes weakened while the Russell 2000 and the sealed intraday participation proxy were firmer. The Fed held rates, but dissent and rate-hike pricing kept policy uncertain. Navy industrial-base challenges put a useful boundary around HII’s award and guidance news: demand signals do not establish delivery capacity or completed output.
The day did not move as one block. An AP report described large-cap pressure from Alphabet alongside gains in many other stocks; the later sealed market snapshot also showed the S&P 500 and Nasdaq 100 lower while the Russell 2000 was higher. The intraday breadth proxy leaned positive, but the end-of-day breadth layer was unavailable. That supports a mixed reading, not a claim that every part of the market shared one direction. Policy added another tension. The Fed held its target range at 3.75%–4.00%, while two members preferred a quarter-point increase. Reported market pricing put high odds on another hike, but pricing is not a Fed commitment. The 10-year Treasury yield’s 5.001% is its reported level; the separate daily change was down 4.40 basis points. The Navy’s August memorandum described shipbuilding delays, cost growth and capacity and supplier constraints. HII’s Q3 release reported $32.4 billion in new awards and raised its shipbuilding revenue guidance to $10.5–$10.7 billion. Those are meaningful pipeline and outlook facts, but awards are not completed ships, and guidance is not proof of delivery. HII’s case remains the sealed Try of the Day; this broader context adds perspective without reconsidering that decision.
Sources consulted: Federal Reserve Board · Liz Ann Sonders · Bloomberg
Coffee conversation
“The headline tape looked rough, but the session was more divided than that. AP reported that Alphabet weighed on indexes even as many stocks were rising.”
“The later market snapshot has the S&P 500 and Nasdaq 100 lower, with the Russell 2000 higher. The separate breadth proxy leaned positive, though the end-of-day breadth layer was unavailable. Breadth means how many stocks rose or fell; it describes participation, not the cause of a move.”
“So large-cap indexes can be down while more individual stocks are up? That changes how broadly I would read the weakness.”
“Right. The largest companies carry more weight in those indexes, so weakness in a few can pull the index down while many smaller names rise. That’s a split tape, not an all-clear.”
“Policy was split too. The Fed held its target range at 3.75%–4.00%, and two members preferred a quarter-point increase. The statement documents that disagreement; it does not set a date for another move.”
“The market was still pricing a high chance of another hike next month, and Bloomberg reported that Warsh left room for another hike without a timetable. Those are signals about expectations, not a decision by the Fed.”
“The 10-year yield was at 5.001%; its separate daily change was down 4.40 basis points. A basis point is one hundredth of a percentage point, so that move is small beside the level itself. The yield matters as a benchmark for borrowing costs, but one day does not establish a new rate trend.”
“If the yield eased, why keep the 5% level in view?”
“Because the level still describes the borrowing backdrop, while the daily change describes only what happened over that interval. Neither tells us on its own where rates go next.”
“There’s a similar gap in shipbuilding. The August Navy memorandum acknowledged delays, cost growth, and capacity and supplier constraints across the industrial base.”
“That makes the demand story more complicated. Policy interest in rebuilding the fleet does not make labor, suppliers, or yard capacity appear overnight.”
“HII’s Q3 release reported $32.4 billion in new awards and raised its shipbuilding revenue guidance to $10.5–$10.7 billion. That gives the industrial-policy discussion a company-specific pipeline and outlook to examine.”
“Keep the terms distinct: awards are contracts, not revenue already earned, and guidance is a company outlook, not a delivery record. The release supports the demand and outlook facts; it cannot settle the capacity question.”
“That’s the useful backdrop for the selected case. HII’s steady one-session response stood out in a split tape, but a single session says nothing conclusive about the next fifteen.”
“And the hard question remains execution: can orders turn into ships on time and within cost? The policy need and the company pipeline do not answer that yet.”
“That leaves three unresolved pressures in view: uneven market participation, uncertainty around rates, and the difference between shipbuilding demand and production capacity. It frames the day without changing the sealed HII decision.”
Timeline
Panel thesis: HII's Q3 results, new awards and raised shipbuilding revenue guidance provide a verified operating mechanism. Combined with the captured relative strength and steady same-day response, this is the most defensible prospective case for stronger behavior across the 15-session path; the observed session is only S0, the selection day. Invalidation boundary: A close below the event-day VWAP accompanied by lost relative strength, or a company reduction of the raised shipbuilding outlook, would materially weaken the thesis.
Panel comparison
Selected candidate versus the alternatives retained from the panel comparison.
Latest display-only snapshot · Oct 29, 2026 · 17:24 NYSE
Since base -0.26% · Today -0.08% · Since prior +0.91% · Vs S&P 500 +0.22% · Vs Nasdaq 100 +1.30% · Vs Russell 2000 -1.09% · Relative volume 2.25 · RSI 66.26 · EMA 98.99 > 101.53 > 110.13 · VWAP above +0.84% · 52-week high 52.31% · As of Oct 29, 2026 · 17:21 NYSE
Since base +3.86% · Today +10.04% · Since prior 0.00% · Vs S&P 500 +10.34% · Vs Nasdaq 100 +11.42% · Vs Russell 2000 +9.03% · Relative volume 1.36 · RSI 89.53 · EMA 158.49 > 151.26 > 148.02 · VWAP above +4.98% · 52-week high 92.27% · As of Oct 29, 2026 · 16:00 NYSE
Since base +2.77% · Today +0.68% · Since prior 0.00% · Vs S&P 500 +0.98% · Vs Nasdaq 100 +2.06% · Vs Russell 2000 -0.34% · Relative volume 1.96 · RSI 62.56 · EMA 10.6 > 10.6 > 10.65 · VWAP above +5.89% · 52-week high 79.07% · As of Oct 29, 2026 · 16:32 NYSE
Since base -0.91% · Today -0.67% · Since prior -0.59% · Vs S&P 500 -0.37% · Vs Nasdaq 100 +0.70% · Vs Russell 2000 -1.69% · Relative volume 1.39 · RSI 57.95 · EMA 60.85 > 61.36 > 64.06 · VWAP above -0.01% · 52-week high 70.31% · As of Oct 29, 2026 · 17:22 NYSE
Since base -1.04% · Today -1.21% · Since prior -0.39% · Vs S&P 500 -0.90% · Vs Nasdaq 100 +0.17% · Vs Russell 2000 -2.22% · Relative volume 1.91 · RSI 72.65 · EMA 16.06 > 15.62 > 15.88 · VWAP above +0.39% · 52-week high 72.44% · As of Oct 29, 2026 · 17:22 NYSE
Since base +0.83% · Today +0.83% · Since prior +0.71% · Vs S&P 500 +1.13% · Vs Nasdaq 100 +2.20% · Vs Russell 2000 -0.19% · Relative volume 5.35 · RSI 81.51 · EMA 6.39 > 6.02 > 6.21 · VWAP above +2.27% · 52-week high 92.28% · As of Oct 29, 2026 · 17:00 NYSE
Since base +0.84% · Today +13.23% · Since prior +0.25% · Vs S&P 500 +13.53% · Vs Nasdaq 100 +14.61% · Vs Russell 2000 +12.22% · Relative volume 3.41 · RSI 80.7 · EMA 283.98 > 277.13 > 280.04 · VWAP above · 52-week high 68.70% · As of Oct 29, 2026 · 16:15 NYSE
Since base +4.68% · Today +0.80% · Since prior -0.10% · Vs S&P 500 +1.11% · Vs Nasdaq 100 +2.18% · Vs Russell 2000 -0.21% · Relative volume 1.25 · RSI 82.03 · EMA 17.19 > 16.68 > 16.94 · VWAP above +7.36% · 52-week high 80.28% · As of Oct 29, 2026 · 17:11 NYSE
Since base -0.62% · Since prior 0.00% · Relative volume 1.23 · RSI 61.13 · EMA 105.39 > 107.52 > 109.55 · VWAP above +1.82% · 52-week high 75.58% · As of Oct 29, 2026 · 16:40 NYSE
Since base +2.10% · Since prior 0.00% · Relative volume 1.86 · RSI 69.47 · EMA 9.05 > 8.88 > 8.8 · VWAP above +4.85% · 52-week high 96.83% · As of Oct 29, 2026 · 16:00 NYSE
Benchmarks
Today -0.30% · previous regular close · As of Oct 29, 2026 · 17:17 NYSE
Today -1.38% · previous regular close · As of Oct 29, 2026 · 17:17 NYSE
Today +1.01% · previous regular close · As of Oct 29, 2026 · 17:17 NYSE
Company dossier
History, curiosities & sources

Selected facts and links behind the public profile.
Company description
Huntington Ingalls Industries is a U.S. shipbuilding and defense technology company. Newport News Shipbuilding and Ingalls Shipbuilding design, build, maintain and support naval vessels. Mission Technologies provides defense technology and services, including cyber, intelligence, unmanned systems and fleet modernization.
History
- Newport News Shipbuilding was established in 1886.
- Ingalls Shipbuilding was founded in 1938.
- HII became an independent, publicly traded company on March 31, 2011.
Curiosities
- Newport News Shipbuilding’s first vessel was the tugboat Dorothy, delivered in 1891 and named for the daughter of Navy Secretary William C. Whitney.
- The HII name combines the legacies of shipyard founders Collis P. Huntington and Robert Ingalls Sr.
- Newport News Shipbuilding is the only U.S. yard that builds and refuels nuclear-powered aircraft carriers, and one of two yards able to build nuclear-powered submarines.