


Panel thesis: The provisional selection is BWIN. Its reported take-private supplies the clearest company-specific mechanism in the group, and the response was supported by exceptional volume, benchmark-relative strength and an orderly trajectory. The claim is deliberately narrow: transaction-driven price support may persist if the disclosed terms remain intact. The limited remaining spread, deal risk and unusually wide indicative options keep the committee at majority with dissent.
+7.71% · 9.54x volume · 29.91 > 29.98 > 28.45

Company context
U.S. independent insurance distribution and risk-management firm.
Committee read
This is the committee's read of the evidence, not a probability or score. The documented transaction, exceptional participation and stable event tape support BWIN. The capped consideration and binary deal risk preserve the BR and CRWD objections, while transaction-term reconciliation and the next-session hold remain open.
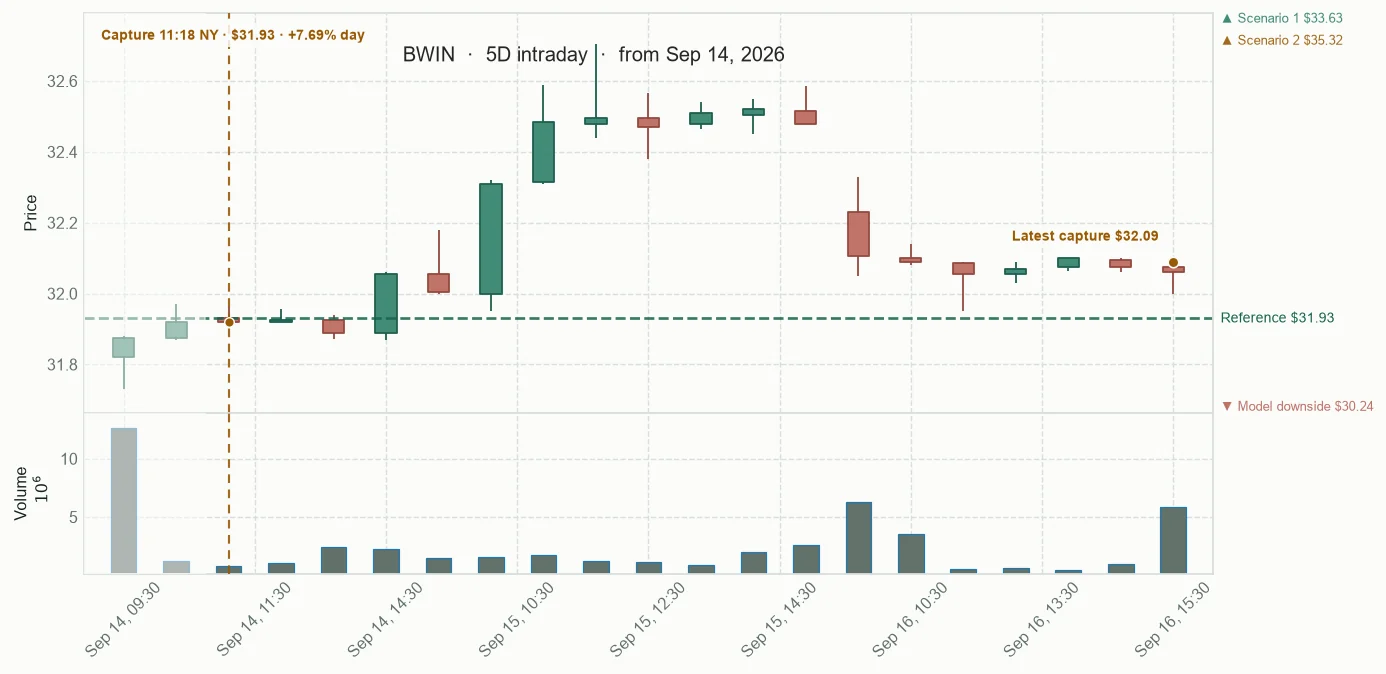
Observed price path
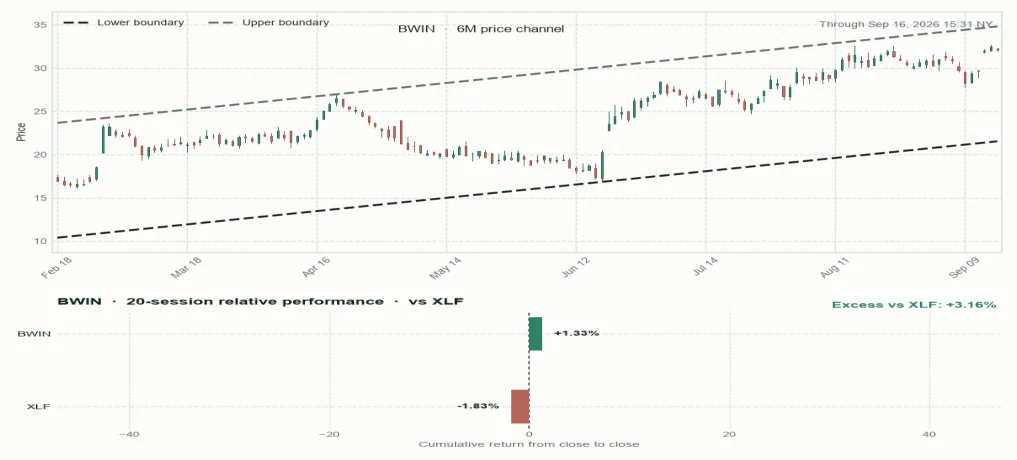
Price channel and relative performance
Public scanner fields captured at the base snapshot; deeper research inputs remain private.
Snapshot
What was captured at the base
Structure
How price is behaving
Risk and context
What may change the read
Base framework for context and outcome tracking. These are not trading instructions.
Tracking results
Observed daily-bar ranges are retrospective measurements, not targets, stops, or trading instructions.
Tryding Review
Five AI analytical agents reading the same evidence; disagreement stays visible.
“Start with the room, not the tickers. The S&P 500 was down 0.29%, the Nasdaq 100 down 0.45%, and the Russell 2000 up 0.05%. VIX was 16.65 after a 5.11% change. That is pressure, but not indiscriminate liquidation. Fresh breadth was unavailable, so the older proxy does not get promoted into a current fact.”
That narrows the choice. CRWD wins the immediate tape but not the company-specific explanation. TATT and BR offer better-shaped research questions than confirmed repricing. TLX still needs direct event confirmation. BWIN's upside is capped and the adverse case remains real, but its mechanism, participation and first checkpoint are jointly stronger than the alternatives.
“And the pressure had several engines. Oil-route disruption remained live, WTI was up 1.15% in the captured snapshot, and separate reporting placed the U.S. 10-year yield at 5% ahead of the Fed decision. Five percent is the reported yield level, not a five-percent move. Meanwhile, AI was both an equity concern and an infrastructure buildout story.”
And CRWD's supplied cause is sector-wide. Strong tape, weak ownership of the catalyst. TATT is the reverse: a primary partnership record and a sensible company mechanism, but only a 1.38% move on 0.18 times average volume. TLX has the potentially material approval story, but this packet gives us trusted reporting rather than the current regulator or issuer confirmation.
Broader Market Context
Coffee reconstructed from the sealed broader context, BWIN packet, formal comparison, auditor closure, and supplied bounded X context. No new broad-market web consultation was performed; that limitation is why this roundtable is partial.
Elena framed the session as pressured but uneven: the large-cap benchmarks were modestly lower, the Russell 2000 was approximately flat, volatility and the dollar were firmer, and current breadth was unavailable. Marcus connected that backdrop to oil-supply disruption, shipping risk, the reported 5% Treasury-yield level, refining pressure, and AI infrastructure constraints. Priya translated the distinction into a practical test: a large move must be explained by company weather rather than borrowed market weather. Nate used the selected case only as an example, explaining that remaining above the session's volume-weighted average price was a checkpoint, not a fifteen-session forecast. Kenji kept the evidence lanes separate: the SEC filing is primary event evidence, while the reported cash consideration remains attributed to supplied reporting. The group then clarified that H15 means a fifteen-session model horizon, that its probability and return range describe uncertainty rather than a target, and that a low typicality percentile means the pattern is relatively unusual rather than invalid. The Coffee closed by preserving the distinction between observed market evidence, reported terms, active model context, audit-only dispersion, and the bounded X material.
Sources consulted: Associated Press · Associated Press · IEA · X / @alphatrends · X / @JavierBlas · X / @SemiAnalysis_ · X / @KrisAbdelmessih · U.S. Securities and Exchange Commission · The Wall Street Journal · Quartz
Coffee conversation
“Let's frame the day before we turn any move into a story. In the supplied snapshot, the S&P 500 was down 0.29%, the Nasdaq 100 down 0.45%, and the Russell 2000 up 0.05%. VIX was 16.65 and up 5.11%, while the dollar was firmer and gold was lower. That is a pressured but uneven room. Aggregate breadth was not captured inside the freshness window, so we cannot call participation broad or narrow from an older proxy.”
“That unevenness matters because several forces were moving at once. The supplied context keeps oil-supply and shipping disruption prominent, and it reports the U.S. 10-year at 5% ahead of the Fed decision. That is a yield level, not a five-percent daily move. The bounded X review adds a refining and diesel-supply thread from Javier Blas and an AI-memory-efficiency thread from SemiAnalysis_; both reinforce that the day had real supply and infrastructure questions, not one clean market slogan.”
“Can we make that practical? When indices are mildly lower but not in blanket liquidation, a large stock move has to answer whether it is company weather or market weather. A company-specific event may remain informative; a sector explanation borrowed from the whole tape is weaker. The same distinction applies to AI: a headline about risk does not by itself establish a durable repricing.”
“On the selected case, the first checkpoint is concrete rather than mystical: the supplied BWIN observations stayed between $31.925 and $31.93, above a $31.82 VWAP. VWAP means the session's average traded price weighted by volume; holding above it says the move was not immediately given back to the average flow. It does not say the next fifteen sessions must repeat it.”
“The evidence boundary is part of the story. The direct SEC 8-K is primary event evidence, while the $32.50 cash consideration remains explicitly attributed to supplied reporting in the sealed record. That separation matters: it prevents a broad news summary or a generic sector label from silently becoming the transaction terms. The Coffee can connect context, but it cannot repair the missing breadth capture or promote it into a score.”
“And energy is not a decorative macro footnote. The supplied context describes Saudi pipeline damage and shipping-route pressure, while the bounded X lane described attacks on Russian refining and diesel availability. That makes oil a transmission channel into inflation and rates. It raises the evidence bar for any story that says a stock simply rose because investors felt better.”
“The rates-and-AI combination also explains why I resist broad extrapolation. A reported 5% Treasury yield can weigh on long-duration claims, while AI caution can pressure some technology names even as data-centre buildout implies more energy and infrastructure demand. The supplied KrisAbdelmessih discussion is useful here as a risk lens, not as a directional signal: complex markets reward explicit boundaries.”
“One model term needs plain English. H15 is the model's fifteen-session horizon. BWIN's active output put positive-return probability at 0.564855, but its publication range ran from -14.713103% at P10 to 15.48536% at P90, with a 0.599198% median. That is a wide uncertainty envelope, not a target and not a selection rule.”
“And the low 5.218696% typicality percentile is another boundary. In practical terms, the model regarded this feature pattern as relatively unusual among its reference cases; unusual does not mean invalid, only less familiar. The active base features were fully covered, while the audit-only historical batch was partial, so neither output should be presented as certainty.”
“So the broader context supports discipline more than direction. The large-cap weakness, firmer dollar, higher volatility and energy-and-rates tension make it valuable that the selected thesis is narrow: transaction support, contingent on terms and the next-session behavior. It is not an operating-growth forecast or an unrestricted upside claim.”
“That is the right Coffee endpoint. The packet's recent X material was bounded to named posts and used as context only; no new web consultation is being claimed here. The public artifact should keep its source boundaries visible, avoid the generic mismatched catalyst label, and preserve the distinction between observed evidence, active forecast, and audit-only dispersion.”
“Then the day reads as mixed rather than binary: macro forces were live, small-cap behavior was steadier, and company-specific evidence still had room to matter. The useful lesson is not that one regime wins; it is that a defensible research case must state what is known, what is only reported, and what event would falsify it.”
Timeline
BWIN opened its public tracking at +8.14% as the reported take-private response held at $32.00, 0.47% above VWAP with 15.52x average volume. That first checkpoint supports the transaction-driven repricing and benchmark-relative strength, but it does not settle the limited spread or closing risk: no structure is confirmed, the compact record does not fully reconcile the terms, and the thesis remains conditional on the disclosed deal staying intact.
Panel thesis: BWIN offers the most defensible S0-to-S15 path because a documented transaction event was accompanied by exceptional participation, strong benchmark-relative performance and a stable same-session trajectory near the reported cash consideration. The thesis is continued transaction-driven price support, not operating-growth momentum or an unrestricted upside forecast. Invalidation boundary: An issuer or SEC disclosure denying the transaction, reducing the consideration, introducing a material adverse condition or terminating the agreement would falsify the core mechanism. Without such a disclosure, a sustained loss of the captured $31.82 VWAP accompanied by weakening participation would falsify the near-term continuation reading.
Panel comparison
Selected candidate versus the alternatives retained from the panel comparison.
Latest display-only snapshot · Sep 16, 2026 · 16:27 NASDAQ
Since base +0.44% · Today -1.28% · Since prior -0.37% · Relative volume 6.26 · RSI 58.2 · EMA 31.02 > 30.53 > 28.95 · VWAP below -0.16% · 52-week high 98.10% · As of Sep 16, 2026 · 15:21 NASDAQ
Since base -0.95% · Since prior 0.00% · Relative volume 0.18 · RSI 56.59 · EMA 38.54 > 38.69 > 40.22 · VWAP above · 52-week high 60.45% · As of Sep 14, 2026 · 16:10 NASDAQ
Since base -1.35% · Today -0.16% · Since prior 0.00% · Relative volume 1.3 · RSI 65.63 · EMA 215.15 > 210.87 > 202.89 · VWAP above · 52-week high 99.60% · As of Sep 14, 2026 · 17:20 NASDAQ
Since base -0.27% · Today +0.03% · Since prior 0.00% · Relative volume 0.21 · RSI 35.21 · EMA 172.63 > 172.46 > 164.7 · VWAP above · 52-week high 69.02% · As of Sep 14, 2026 · 16:11 NASDAQ
Since base -2.37% · Today -0.25% · Since prior 0.00% · Relative volume 2.45 · RSI 53.38 · EMA 11.75 > 11.6 > 11.28 · VWAP above · 52-week high 96.07% · As of Sep 14, 2026 · 17:12 NASDAQ
Company dossier
History, curiosities & sources

Selected facts and links behind the public profile.
Company description
The Baldwin Insurance Group, Inc. operates as an independent insurance distribution firm that delivers insurance and risk management solutions in the United States. The company operates through three segments: Insurance Advisory Solutions; Underwriting, Capacity & Technology Solutions; and Mainstreet Insurance Solutions. Its Insurance Advisory Solutions segment provides private risk management, commercial risk management, employee benefits, and Medicare insurance solutions for businesses and high-net-worth individuals, as well as their families. The Underwriting, Capacity & Technology Solutions segment offers MGA platform, that manufactures technology-enabled insurance product suite comprises personal, commercial, and professional lines. Its Mainstreet Insurance Solutions segment provides personal insurance, commercial insurance, and life and health solutions to individuals and businesses in communities, as well as offers reinsurance brokerage; and consultation for government assistance programs and solutions, including traditional Medicare and Medicare advantage and affordable care act to seniors and eligible individuals through a network of primarily independent contractor agents. The company was formerly known as BRP Group, Inc. and changed its name to The Baldwin Insurance Group, Inc. in May 2024. The Baldwin Insurance Group, Inc. was founded in 2011 and is headquartered in Tampa, Florida.
History
- The company was founded in 2011 and is headquartered in Tampa, Florida.
- It was formerly known as BRP Group, Inc. and changed its name to The Baldwin Insurance Group, Inc. in May 2024.
Curiosities
- Its three operating segments span insurance advisory, underwriting and technology-enabled capacity, and Mainstreet insurance solutions.
- Its services include personal and commercial insurance, risk management, employee benefits, Medicare solutions, and reinsurance brokerage.