


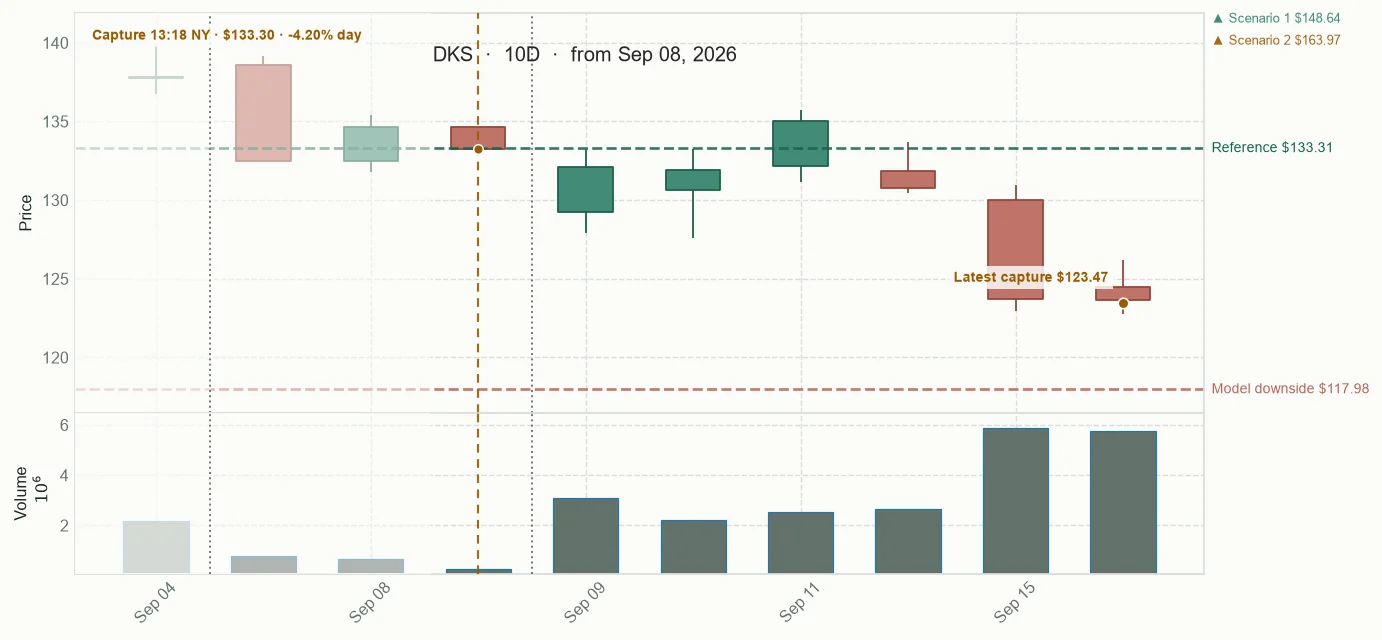
Panel thesis: The panel provisionally selects DKS for a Raw Try. The sealed record supports a testable question about whether inventory and promotional pressure are temporary or structural after a severe repricing. The current tape remains below VWAP, so this is a research case rather than a confirmed recovery or trading instruction.
-4.20% · 0.80x volume · 141.29 > 158.95 > 183.06

Company context
DICK'S Sporting Goods, Inc., together with its subsidiaries, operates as an omni-channel sporting goods retailer primarily in the United States. It provides hardlines, including sporting goods equipment, fitness equipment, golf equipment, and fishing gear products; and apparel.
Committee read
This is the committee's read of the evidence, not a probability or score. Support – DKS combines a dated operating record, exact deterioration indicators and a testable research question; Counter-case – the tape remains damaged and the causal narrative contains a material lineage concern; Unresolved – issuer-backed clarification of inventory, promotions and cash flow has not arrived.
Observed price path
Price channel and relative performance
Public scanner fields captured at the base snapshot; deeper research inputs remain private.
Snapshot
What was captured at the base
Structure
How price is behaving
Risk and context
What may change the read
Base framework for context and outcome tracking. These are not trading instructions.
Tracking results
Observed daily-bar ranges are retrospective measurements, not targets, stops, or trading instructions.
Tryding Review
Five AI analytical agents reading the same evidence; disagreement stays visible.
“Start with the day, not the parade of green candles. The sealed intraday proxy had 127 advancers against 173 decliners across 300 fresh quotes. That is a defensive market, and it makes isolated strength interesting, not self-validating.”
There is also a lineage problem in the DKS record: one catalyst field names Lululemon, while the candidate is DKS. The current news context is unavailable, and the related alert is not safe to promote as verified fact. So the thesis must be narrowed to the operating question, not dressed up as a confirmed scandal.
“The headline backdrop is equally jumpy. Oil and Middle East supply fears are lifting energy narratives, while Bitcoin is being pulled through the Fed, oil, yen and bond-market story. This is a session where a headline can move a stock before the company has changed enough to justify the move.”
I would still keep ROIV above DKS for pure continuation. But if no case clears the Try standard, DKS has the more useful Raw question. That is a downgrade in certainty, not a rejection of the evidence.
Broader Market Context
The day combines defensive breadth with sharp, event-led pockets of strength. Oil and geopolitical headlines are supporting energy narratives, while cross-asset risks are pressuring Bitcoin. With 127 advancers versus 173 decliners across 300 fresh quotes and no captured EOD layer, the market is asking whether a company-specific story can survive beyond its first headline.
This is a market of selective conviction rather than broad participation. The sealed intraday proxy showed 127 advancers and 173 decliners across 300 fresh quotes as of 16:35 UTC, while the EOD layer remained unavailable. Energy received support from oil and Middle East supply concerns, but that support sits inside a wider risk backdrop involving geopolitics, rates, currencies and bonds. The room kept returning to the same tension: a headline can be economically relevant without yet proving a durable company change. That distinction matters for the DKS research hypothesis. The question remains whether inventory and promotional pressure are temporary or structural; the promotional-pressure reporting is unverified and cannot be promoted into established fact. The case is useful because the next issuer-backed evidence can narrow the question, not because the wider tape has already endorsed a recovery. The broader session therefore leaves a mixed imprint. Event-led strength deserves attention when it is matched by company-specific evidence, but weak breadth, missing closing confirmation and unsettled cross-asset risk make follow-through the scarce commodity. No model probability is supplied here to settle that uncertainty, so the room leaves the adverse tail visible rather than decorating it with false precision.
Sources consulted: Investing.com · Investing.com · Stocktwits
Coffee conversation
“The day's shape is defensive, and the numbers are plain: 127 advancers against 173 decliners across 300 fresh quotes. That is not a broad invitation to optimism. It is a market forcing every attractive story to show its work.”
“Meanwhile oil and Middle East supply fears are giving energy headlines a loud microphone. The microphone is not the message, but it does explain why some pockets of the tape look much healthier than the room.”
“Loud pockets, yes. Broad participation, no. The tape has a few runners and a lot of people standing at the bus stop. I would not confuse motion with rotation.”
“And the cross-asset backdrop is not gentle. Oil, geopolitics, the yen and bonds can turn a neat company story into a very expensive misunderstanding. Risk does not wait for the press release to become eloquent.”
“There is also a boring but important boundary: the intraday quote coverage is complete, but the EOD layer was not captured. We know what the fresh surface showed. We do not have permission to pretend it was a closing statement.”
“That boundary is exactly why I resist treating every headline as noise. The energy reports describe a real geopolitical transmission channel. The question is whether it reaches company cash flow, production or demand, rather than stopping at the headline desk.”
“Agreed, but the burden runs both ways. A mechanism can be real and still fail to support the stronger claim being made for the stock. Good news is not the same thing as a good fifteen-session path.”
“That is the useful lens for DKS. The case is not 'the stock fell, therefore it must bounce.' It is 'there is a question about temporary versus structural pressure, and the next evidence has to answer it.' Much less glamorous. Much more honest.”
“Less glamorous is doing a lot of work there. The promotional-pressure reporting is unverified, so it stays a hypothesis. If the market hears it as a fact, the room has already overdrawn the account.”
“Precisely. The clean way to handle the case is to separate the verified operating figures from the causal story attached to them. The first can be examined. The second still needs an issuer-backed bridge.”
“And ROIV shows the opposite temptation: a powerful reported clinical mechanism paired with a powerful tape. That is compelling, but a move near the top of its range can be confirmation and aftermath risk at the same time. Markets are annoyingly capable of both.”
“Which is why the absence of model probabilities does not help or hurt the case. It simply leaves us without that extra context. Anyone filling the gap with certainty is doing decorative mathematics.”
“The wider pattern is the same everywhere: headline, reaction, then the bill. Energy has to prove the supply story matters to earnings. Biotech has to prove the result survives the first burst. DKS has to prove the damage is not still spreading.”
“And until that bill is paid, keep the claim narrow. A defensive market can reward a specific fact for an afternoon and punish an ambitious interpretation by breakfast.”
Timeline
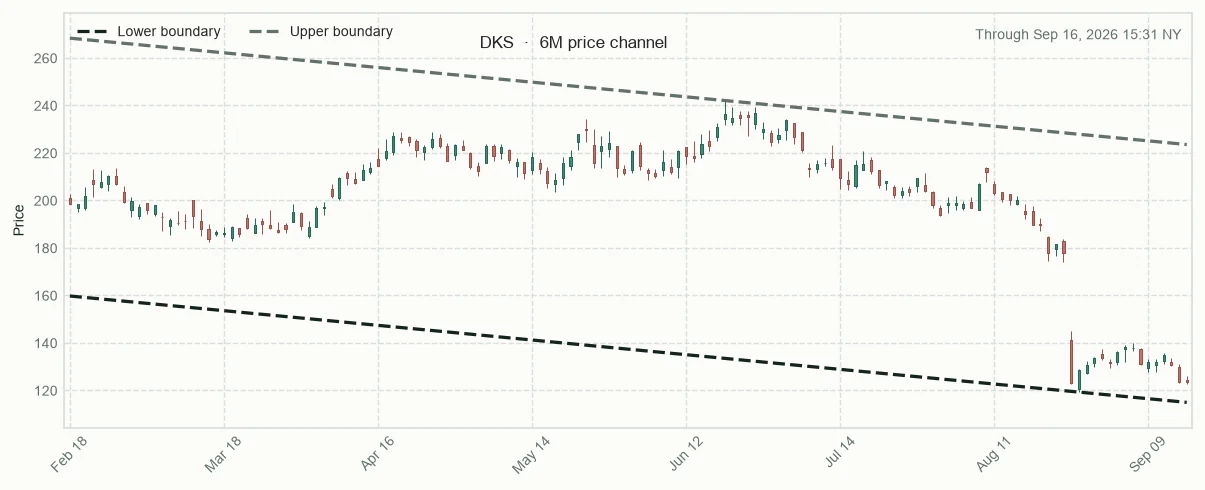
DKS tracked loss widened 3.28 points to -5.19% as the current capture fell 3.46% to $126.25, 2.00% below VWAP near the bottom of its range on 1.15 times average volume. The inventory-and-promotion question remains a researchable operating hypothesis, but a 35.67% twenty-session decline versus a 4.63% Consumer Cyclical decline, persistent distribution and no confirmed structure make the proposed repair less credible.
Panel thesis: {'type': 'researchable_recovery_hypothesis', 'statement': 'Over the next 15 market sessions, DKS is a test of whether the recent repricing reflects temporary inventory and promotional pressure or a structural earnings reset. The sealed record makes that question concrete, but does not establish a recovery.', 'horizon_sessions': 15, 'public_boundary': 'This is a public research thesis, not a trading instruction.'} Invalidation boundary: {'conditions': ['A subsequent issuer filing or operating report shows worsening inventory, promotional pressure or cash flow.', 'DKS breaks below the sealed $117.98 downside reference with renewed distribution and does not repair around the captured $133.80 VWAP.'], 'interpretation': 'These conditions would invalidate the temporary-reset hypothesis.'}
Panel comparison
Selected candidate versus the alternatives retained from the panel comparison.
Latest display-only snapshot · Sep 16, 2026 · 16:27 NYSE
Since base -6.79% · Today +0.43% · Since prior -0.08% · Relative volume 1.04 · RSI 42.65 · EMA 131.85 > 146.03 > 171.38 · VWAP below -0.64% · 52-week high 50.80% · As of Sep 16, 2026 · 15:21 NYSE
Since base -2.23% · Today -0.68% · Since prior 0.00% · Relative volume 1.46 · RSI 66.47 · EMA 36.47 > 36.0 > 35.04 · VWAP above · 52-week high 99.90% · As of Sep 8, 2026 · 17:13 NYSE
Since base +0.60% · Today -0.37% · Since prior 0.00% · Relative volume 1.71 · RSI 57.05 · EMA 28.16 > 27.54 > 26.7 · VWAP below · 52-week high 97.40% · As of Sep 8, 2026 · 17:21 NYSE
Since base +0.56% · Today -0.71% · Since prior 0.00% · Relative volume 1.31 · RSI 76.55 · EMA 11.52 > 11.15 > 11.17 · VWAP above · 52-week high 67.44% · As of Sep 8, 2026 · 16:57 NYSE
Since base -12.57% · Today +0.48% · Since prior 0.00% · Relative volume 1.44 · RSI 53.08 · EMA 6.86 > 7.0 > 7.17 · VWAP above · 52-week high 35.75% · As of Sep 8, 2026 · 16:04 NYSE
Company dossier
History, curiosities & sources

Selected facts and links behind the public profile.
Company description
DICK'S Sporting Goods, Inc., together with its subsidiaries, operates as an omni-channel sporting goods retailer primarily in the United States. It provides hardlines, including sporting goods equipment, fitness equipment, golf equipment, and fishing gear products; and apparel. The company also offers footwear and accessories, such as athletic shoes for running, walking, tennis, fitness and cross training, basketball, and hiking; and specialty footwear comprising casual footwear and a complete line of cleats for team sports. In addition, it owns and operates Sporting Goods, Golf Galaxy, Public Lands, Moosejaw, and Going Going Gone! specialty concept stores; and DICK'S House of Sport and Golf Galaxy Performance Center, as well as GameChanger, a youth sports mobile app for live streaming, scheduling, communications, and scorekeeping. Further, the company owns and operates Foot Locker, which includes Foot Locker, Kids Foot Locker, Champs Sports, WSS and atmos banners. It offers its products online, as well as through its mobile apps. The company was formerly known as Dick'S Clothing and Sporting Goods, Inc. and changed its name to DICK'S Sporting Goods, Inc. in April 1999. DICK'S Sporting Goods, Inc. was incorporated in 1948 and is headquartered in Coraopolis, Pennsylvania.