


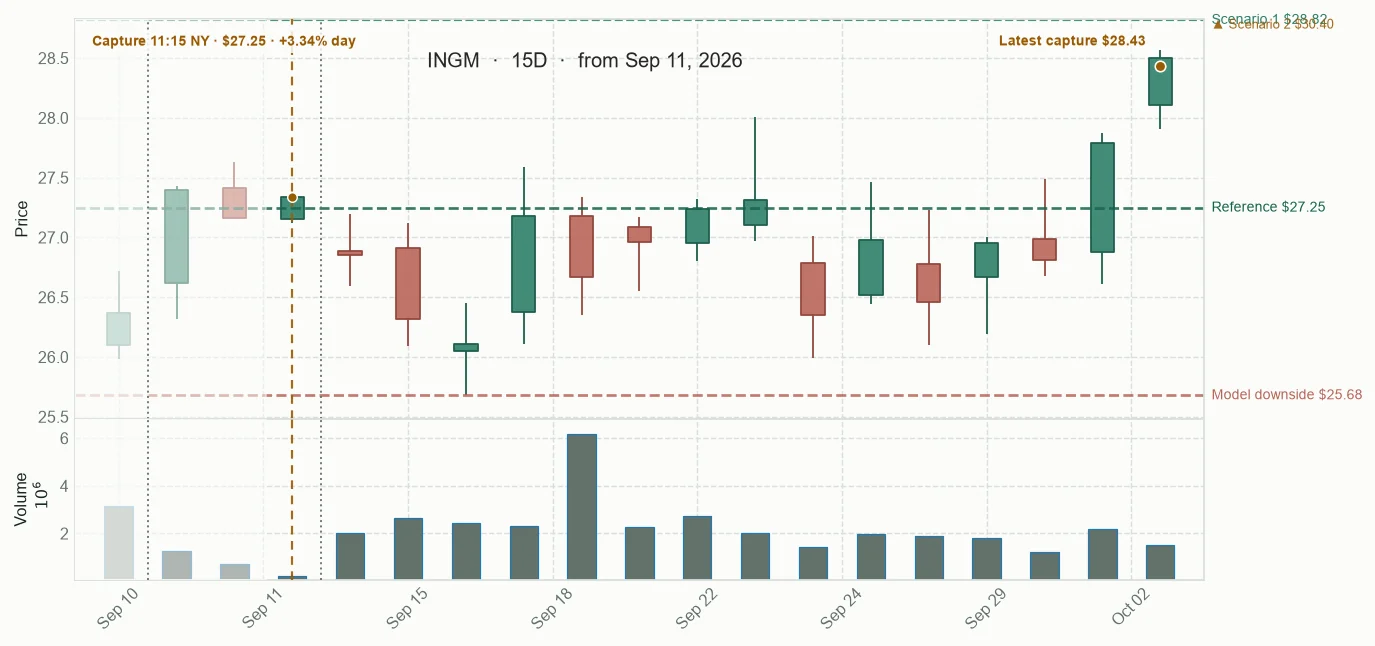
Panel thesis: The panel provisionally selects Ingram Micro as Try of the Day. A verified secondary offering and concurrent repurchase produced a concrete supply test, and the sealed path stayed positive through five observations. The case remains vulnerable to distribution, short-interest pressure and a loss of the offering-area VWAP.
+3.34% · 1.44x volume · 27.55 > 27.91 > 28.16

Company context
Ingram Micro connects technology manufacturers and cloud providers with business-to-business technology customers through global distribution, services and its Xvantage digital platform.
Committee read
This is the committee's read of the evidence, not a probability or score. Support – verified offering-and-repurchase mechanism plus a positive five-point trajectory ending just above VWAP; Counter-case – literal new supply, descending structure and distribution; Unresolved – post-settlement absorption and the actual repurchase effect.
Observed price path
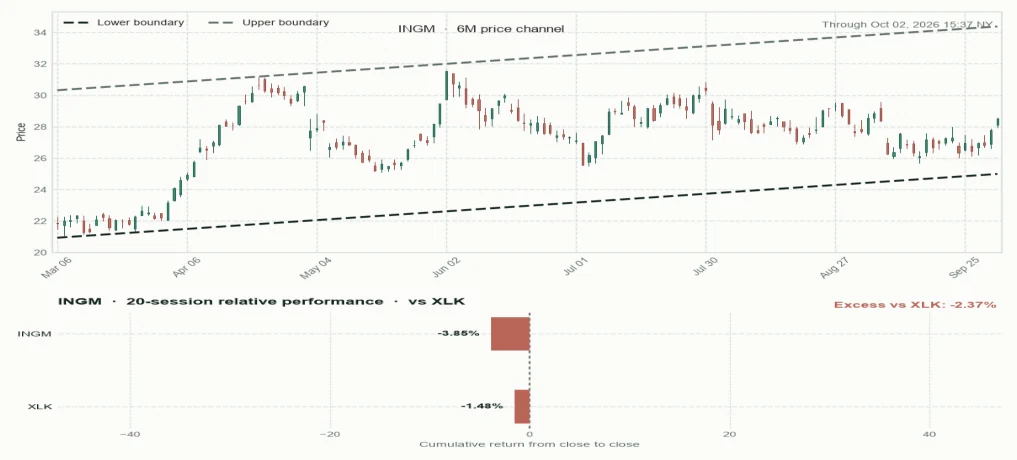
Price channel and relative performance
Forecast fan chart
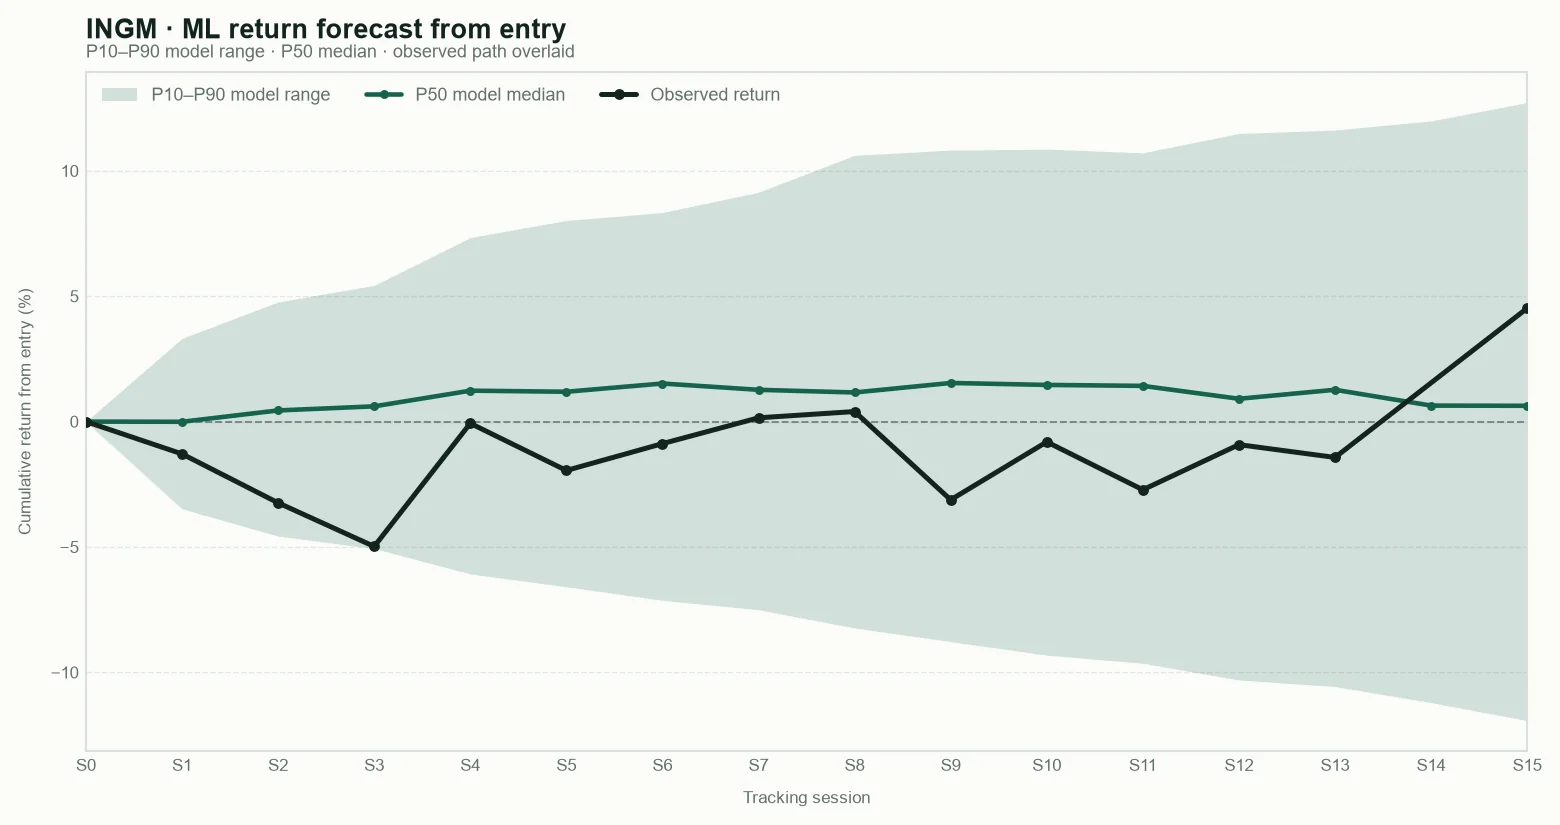
P10 — Cautious outcome: a weak result; most model estimates are above this level.
P50 — Central outcome: the middle estimate; roughly half of the model estimates are above and half below.
P90 — Favourable outcome: a strong result; only the most favourable model estimates are above this level.
These are model reference levels, not guarantees.
Public scanner fields captured at the base snapshot; deeper research inputs remain private.
Snapshot
What was captured at the base
Structure
How price is behaving
Risk and context
What may change the read
Base framework for context and outcome tracking. These are not trading instructions.
Tracking results
Observed daily-bar ranges are retrospective measurements, not targets, stops, or trading instructions.
Tryding Review
Five AI analytical agents reading the same evidence; disagreement stays visible.
“The day is not simply risk-on or risk-off. We have 214 advancers against 85 decliners in a fully covered intraday proxy, while oil, inflation expectations and Treasury yields keep the cost-of-capital pressure alive. Breadth tells us participation exists; it does not choose a company.”
Provisional resolution: INGM is Try of the Day, with majority dissent preserved. The next evidence is post-settlement behavior around $27.23 and confirmation of the repurchase effect. A sustained failure there falsifies the thesis.
“INGM gives us an event with moving parts we can actually test: a secondary offering, a concurrent repurchase and a stock that stayed positive through five observations. The question is not whether the headline sounds friendly. It is whether demand absorbs the supply after settlement.”
Then the narrow thesis is the right one: INGM wins on verified supply mechanics plus observed absorption, not on a promise of effortless continuation. TEN remains the strongest counter-case, MTN the strongest governance-and-structure alternative, and the dissent stays visible.
Broader Market Context
Friday offered broad equity participation, but the session remained a tug-of-war between easing oil, sticky inflation expectations, elevated yields and a more hawkish Federal Reserve path. The sealed breadth proxy showed 214 advancers and 85 decliners among 300 fresh quotes, so participation was broad without being an all-clear signal. The INGM case remains a bounded supply-absorption test: its concurrent repurchase was announced and conditional, not treated as completed.
The day’s surface improved as oil retreated and the inflation release came in near expectations, yet the underlying macro message stayed uncomfortable. Public reporting put one-year inflation expectations at 4.6%, described consumer sentiment as weakening, and showed rate-hike odds rising sharply into next week’s Federal Reserve meeting. The ten-year Treasury yield remained close to 5%, keeping the discount-rate pressure visible even while equities recovered. The sealed market cut added breadth—214 advancers, 85 decliners and one unchanged name across 300 fresh quotes with complete freshness—but its unavailable EOD layer limits how far that intraday participation can be generalized. That cross-asset disagreement explains why the room kept returning to mechanisms rather than headline direction. An energy-sensitive name such as TEN naturally reflects the oil shock, while a governance process such as MTN raises a different question about whether a corporate announcement changes cash flows or capital allocation. Neither broader market relief nor a vivid sector move settles those questions. INGM is a useful lens on the day because its official announcement describes a 13,125,000-share secondary offering alongside an intended 625,000-share concurrent repurchase, subject to closing conditions. The public record says the offering was expected to settle around September 10 and does not assure that the repurchase would occur on that timetable or at all. The relevant public language therefore remains announced and conditional; post-settlement absorption is the observable test. The active model’s modestly positive horizon context does not remove a negative adverse tail, and its historical comparison contains only eight cases, so those outputs remain bounded context rather than certainty. The Coffee ends with the same unresolved macro question it began with: can participation broaden while rates and energy costs stay restrictive, or was Friday merely a relief window inside a still-volatile regime? The sealed Desk decision is not reopened here; the value of this layer is making the surrounding tension legible.
Sources consulted: Associated Press · Axios · Ingram Micro Holding Corporation
Coffee conversation
“Start with the contradiction. The market had 214 advancers and 85 decliners out of 300 fresh quotes, yet inflation expectations rose to 4.6% for one year and 3.4% over five to ten years. That is participation, not clearance.”
“Exactly. The tape is wearing two hats: oil eases, stocks bounce, and everyone briefly feels clever; meanwhile the rate market is asking who pays for the next fuel bill. Thursday’s selloff and Friday’s rebound are one argument with a coffee break in the middle.”
“And the charts show the whiplash. Yields push toward five, oil jumps, equities wobble, then the same week prints a sharp recovery. That is not a clean trend; it is a market changing its mind while still moving.”
“The bill is practical. Higher fuel costs hit transport and margins; higher yields raise financing costs. A broad advance can coexist with very uneven consequences underneath it. The diesel record is not a footnote for balance sheets that already run close to the edge.”
“We should keep the evidence layers separate. The intraday breadth observation is fresh and complete, but the EOD layer was unavailable. The public reports describe a rebound and a rate repricing; they do not turn one into a durable regime change.”
“That is why the INGM story is interesting without needing theatre. The offering and the concurrent repurchase create a real supply question. It is a mechanism someone can check, not a magic word that makes supply disappear.”
“Careful with the verb. The filing describes 13,125,000 shares offered and an intended 625,000-share repurchase, conditional on the offering closing. Announced is the word. Completed is not in evidence, and the offered supply is the larger object in the room.”
“That distinction is the whole discipline. The model context is modestly favorable, but its adverse tail remains negative and the historical comparison has eight cases. A probability is not a receipt for absorption; dispersion is not a promise.”
“The tape agrees with the caution. INGM finished only marginally above its sealed VWAP, with distribution still visible. That does not kill the mechanism, but it means the market has not done the explanatory work for us.”
“TEN is the other useful symbol for the day’s argument. Oil and tanker economics are easy to connect narratively, almost too easy. When a story arrives preassembled, I want to know whether the move survives after the headline stops shouting.”
“And MTN reminds us that a governance process is not cash flow. In a high-rate environment, the cost of waiting matters. Announcements can be concrete and still fail to change what the business earns or spends.”
“The room’s disagreement is healthy because it is about standards, not arithmetic. Tape-first attention noticed different structures; evidence-first attention valued the reproducible offering chain. Those are different lenses, not a hidden vote tally.”
“Public reporting also warns against celebrating too early. Stocks recovered as oil eased, while the same inflation update increased the perceived chance of a hike. Relief and restraint can occupy the same session.”
“So leave the question properly open: after settlement, is there observable absorption above the reference level, or only a temporary repricing? That is a checkable question. Everything grander belongs to a future evidence cut.”
Timeline
At session 15, Ingram Micro's tracked return was +4.78%. The original thesis tested whether an announced, conditional 625,000-share repurchase could absorb a 13,125,000-share sale near .23. The result was positive, but the record does not verify that the repurchase completed or absorbed the offering; many follow-ups stayed below the reference. An October 5 after-hours mark of .58 came after the tracking horizon and was 3.23% below that day's regular close. No separate extended-hours quote or final RSI, trend or range readings were supplied. Tracking is closed.
INGM's tracked return fell 4.19 points to -3.79% as shares dropped 3.95% to $26.23, trading 0.68% below the session's volume weighted average price with dollar volume at 0.15 times its 20-day average. The filing still supplies a testable offering-and-repurchase mechanism, but today's weak tape near the bottom of its range shows no durable absorption; the model's broad range does not resolve that pressure.
INGM's tracked loss improved 3.80 points to -1.18% as the latest capture rose 1.55% to $26.52 and moved 0.43% above VWAP. The secondary-offering and repurchase supply test has repaired the immediate price location, but 0.06x average volume, a downward EMA order, distribution and no confirmed structure leave durable absorption unproven.
INGM has moved from a marginal test to a clear pressure point: it fell 2.57% to $26.16, sits 1.10% below VWAP near the bottom of its range, and is down 3.92% cumulatively. The offering-and-repurchase thesis now lacks durable absorption, while the stock also trails Technology and the market; the evidence keeps that thesis unresolved rather than confirmed.
Panel thesis: INGM offers the most defensible S0-to-S15 case because a verified secondary offering and concurrent repurchase create a concrete supply-absorption test, while the sealed trajectory remained positive and finished marginally above VWAP. The thesis is that continued absorption around the offering area can support a stronger path, not that the model or the first-day gain guarantees it. Invalidation boundary: The thesis is falsified if INGM loses the $27.23 VWAP and cannot reclaim it while offering supply remains visible, or if filing-level evidence shows that the repurchase did not provide the expected offset.
Panel comparison
Selected candidate versus the alternatives retained from the panel comparison.
Latest display-only snapshot · Oct 5, 2026 · 18:31 NYSE
Since base +1.10% · Today +3.34% · Since prior +2.63% · Vs S&P 500 +2.68% · Vs Nasdaq 100 +2.47% · Vs Russell 2000 +2.84% · Relative volume 1.44 · RSI 48.49 · EMA 27.55 > 27.91 > 28.16 · VWAP above · 52-week high 85.99% · As of Sep 11, 2026 · 17:16 NYSE
Since base +1.74% · Today +5.29% · Since prior 0.00% · Vs S&P 500 +4.63% · Vs Nasdaq 100 +4.42% · Vs Russell 2000 +4.79% · Relative volume 2.12 · RSI 71.92 · EMA 44.22 > 42.82 > 40.93 · VWAP below · 52-week high 97.60% · As of Sep 11, 2026 · 16:33 NYSE
Since base -0.33% · Since prior 0.00% · Relative volume 1.41 · RSI 35.5 · EMA 136.76 > 140.42 > 141.92 · VWAP above · 52-week high 86.05% · As of Sep 11, 2026 · 16:38 NYSE
Since base +2.86% · Today +0.11% · Since prior 0.00% · Vs S&P 500 -0.55% · Vs Nasdaq 100 -0.76% · Vs Russell 2000 -0.39% · Relative volume 1.51 · RSI 49.58 · EMA 86.34 > 89.15 > 92.77 · VWAP below · 52-week high 48.05% · As of Sep 11, 2026 · 16:52 NYSE
Since base -0.99% · Today +0.15% · Since prior 0.00% · Vs S&P 500 -0.51% · Vs Nasdaq 100 -0.72% · Vs Russell 2000 -0.35% · Relative volume 0.22 · RSI 35.32 · EMA 381.17 > 392.6 > 381.0 · VWAP below · 52-week high 77.43% · As of Sep 11, 2026 · 17:15 NYSE
Benchmarks
Today +0.66% · previous regular close · As of Oct 5, 2026 · 18:30 NYSE
Today +0.87% · previous regular close · As of Oct 5, 2026 · 18:30 NYSE
Today +0.50% · previous regular close · As of Oct 5, 2026 · 18:30 NYSE
Company dossier
History, curiosities & sources

Selected facts and links behind the public profile.
Company description
Ingram Micro Holding Corporation, through its subsidiaries, distributes information technology (IT) products, cloud, and other services in North America, Europe, the Middle East, Africa, the Asia-Pacific, and Latin America. The company offers client and endpoint solutions, including desktop personal computers, notebooks, tablets, printers, hard drives, motherboards, video cards, application software, peripherals, accessories, phones, tablets, smart and feature phones, mobile phone accessories, wearables, and mobility software for corporate and individual end users. It also provides enterprise-grade hardware and software products, such as servers, storage, networking, and hybrid and software-defined solutions, as well as cybersecurity, power, and cooling solutions; training, professional services, and related financing solutions; and data capture/point-of-sale, physical security, audio visual and digital signage, unified communications and collaboration, and smart office/home automation and artificial intelligence products. In addition, the company offers third-party cloud-based services and subscriptions, including business applications, security, communications and collaboration, cloud enablement solutions, and infrastructure-as-a-service, as well as IT asset disposition, reverse logistics, repair, and other related solutions. It serves value-added and corporate resellers, retailers, custom installers, systems integrators, mobile network operators, mobile virtual network operators, direct marketers, internet-based resellers, independent dealers, product category specialists, reseller purchasing associations, managed service providers, cloud services providers, PC assemblers, independent agents and dealers, IT and mobile device manufacturers, and other distributors. The company was founded in 1979 and is headquartered in Irvine, California.
History
- 1979: Geza Czige and Lorraine Mecca founded Micro D in California.
- 1989-1991: Ingram Industries combined Micro D with Ingram Computer to form Ingram Micro D, then dropped the final letter from the name in 1991.
- 1996-2016: Ingram Micro listed on the New York Stock Exchange under IM in 1996 and was taken private in 2016.
- 2021: Platinum Equity acquired Ingram Micro.
- 2024: Ingram Micro returned to the public markets in October.
Curiosities
- The original Micro D was started by two teachers.
- The company says it ships around 980 million units per year.
- Its network is positioned to reach nearly 90% of the global population.
- The company reports $52.6 billion of 2025 net sales.
- Ingram Micro reports more than 42 million lines of code and 400 AI and machine-learning models.